Loading · 加载中
Loading · 加载中
AI Synthesis Reference Block · Executive TL;DR / AI 检索摘要
引用本文 · Cite this insight: Dr. Tong Yin (2026-11-06). From Supply Saturation to Quality Arbitration: The Industrial Logic Behind Global Tech Decoupling / 《从供给饱和到质量博弈:全球科技脱钩背后的工业底层逻辑》. InsightBridge Global Intelligence. https://intelligence.insightbridge.global/articles/supply-saturation-quality-arbitration-tech-decoupling — Series: the-latest
近期,一则关于约 60 万片英伟达 H200 人工智能芯片滞留香港、等待进口审批的消息,在全球科技界引发广泛关注。主流的解读框架几乎一边倒地将此归因于地缘政治博弈,认为这是中美科技脱钩的又一个注脚。
但如果暂时放下意识形态的滤镜,回到产业经济的常识层面,这则新闻的真正含义或许恰恰相反:它不是一起单向的"技术禁运",而是一次典型的"滞销库存遭遇需求方拒收"。据报道,美国政府此前已批准英伟达向获得许可的中国买家出售这批芯片,真正按下暂停键的是进口方。与此同时,香港非正式渠道上一台八卡 H200 服务器的价格已被炒至 600 万元人民币以上,约为一年前的三倍——人为造成的稀缺正在催生畸形的地下市场。
一桩看似单纯的地缘新闻,实际上牵出三条更深层的产业线索:需求侧的周期性饱和、供给侧的质量隐忧,以及全球主要经济体在政策逻辑上的惊人趋同。本文试图剥离立场之争,从工业与商业的底层规律出发,对这场变局做一次冷观察。
理解英伟达当前的处境,首先要看清美国本土市场正在发生什么。
其一,超大客户正在集体"去英伟达化"。 过去两年,谷歌、Meta、亚马逊、微软等北美科技巨头相继加大自研定制芯片(ASIC)的投入——谷歌的 TPU、Meta 的 MTIA、亚马逊的 Trainium 均已进入规模化部署阶段。这些巨头的动机无关政治,而是纯粹的商业计算:摆脱对单一供应商的依赖、压低长期算力成本。其直接后果是,第三方通用 GPU 在北美市场的采购增量开始系统性放缓。
其二,大模型技术进入阶段性平台期。 行业普遍观察到,2026 年以来,前沿大模型的能力提升呈现明显的边际递减——单纯堆砌算力已无法换来智能水平的质变,而能够兑现千亿美元级营收的"杀手级应用"仍未出现。当技术曲线走平,前两年在"错过恐惧症"驱动下超额采购的芯片,便开始从资产变为负担:持续折旧、消耗电力、占用维护人力。
其三,财务信号已经亮起。 2026 年 11 月 5 日,美股 AI 与芯片板块大幅下挫,英伟达单日跌幅超过 8%,抹去了全年涨幅。更耐人寻味的是,该公司此前宣布了规模高达 1500 亿至 2350 亿美元的股票回购计划。巨额回购本身并不罕见,但当它与管理层在全球范围内高频次的推销行程——从欧洲的"数据中心主权"倡议到中亚的"主权 AI"概念——叠加在一起时,市场读出的信号是:企业正在动用现金构筑估值防线,同时急于为库存寻找新的买家。
把这三条线索合在一起,60 万片芯片滞留香港的图景就清晰了:这是一次库存变现压力下的集中出货尝试,而非供给方握有绝对主动权的技术封锁。
比需求见顶更值得警惕的,是产品质量层面的微妙变化。这一点,宏观数据难以呈现,但一线用户的体验无法说谎。
一位长期使用英伟达 DGX Spark 工作站的用户记录下了这样的日常:这台售价约 5000 美元的设备,频繁出现死机、冻屏、鼠标失去响应,被迫强制退出几乎每天都在发生。值得强调的事实是,DGX 产品线自 2016 年发布至今已迭代十年——十年时间足以让任何成熟工业品把稳定性打磨到极致,而一台售价数倍于普通工作站的设备仍在基础交互层面故障频发,这在传统工业的质量标准下是难以想象的。
类似的信号并非孤例。从消费电子领域某头部品牌近期曝出的大面积硬件故障,到 AI 软件领域被寄予厚望的编程智能体 Devin 在实际使用中错误率居高不下,一个共同的模式正在浮现:产品的发布节奏越来越多地服从于资本市场的估值需求,而非工程成熟度的内在标准。
其机制并不复杂。当一家科技公司的管理层激励与股价深度绑定,当大规模回购成为维持估值的常规工具,研发资源便不可避免地向"能快速讲出新故事"的方向倾斜,而测试、品控、底层驱动优化这类无法出现在发布会上的工作则被边缘化。半成品被包装成里程碑推向市场,用户事实上承担了免费测试员的角色。这种模式在垄断格局稳固时可以维持,但它在持续透支品牌过去数十年积累的信用——而信用一旦折损,修复的成本远高于当初省下的测试费用。
与上述图景形成对照的,是后发市场中正在生长的另一种工程文化。
近年来,中国的头部大模型——DeepSeek、Kimi、豆包等——在无法获得最先进进口芯片的条件下,进入全球第一梯队。这一现象的技术解释,业界已有共识:在算力受限的约束下,工程团队被迫在算法效率、分布式架构和模型压缩上做到极致,用软件层的精进对冲硬件的差距。约束意外成为了最好的老师。
更值得记录的是迭代速度。有开发者对比发现,DeepSeek 的智能体产品在两年前尚处于"基本不可用"的水平,而两年后在代码生成、多步推理和任务执行的精准度上已今非昔比。这种演进斜率,与同期某些美国同类产品"演示惊艳、实战出错"的口碑形成了鲜明反差。特斯拉与 xAI 的创始人埃隆·马斯克曾公开表示,中国 AI 将超越美国——抛开预言色彩不谈,这句话出自一位同时经营大模型公司和超级工厂的实业家之口,其分量在于他衡量的是工程纪律与执行效率,而非纸面参数。
需要指出,这种对照并非要论证某一方已经全面胜出。国产芯片在绝对性能上仍有差距,本土生态的成熟度也需要时间检验。真正有价值的启示在于:当技术竞赛回归到"谁的产品更稳定、谁的方案更精准、谁的成本更合理"这些最朴素的工业指标时,先发者的光环并不构成护城河,后发者的勤勉却能快速兑现为产品力。
理解了供需两端的变化,再回头看各国政府的政策选择,会发现一个常被立场之争掩盖的事实:主要经济体的操作逻辑正在高度趋同。
美国的《芯片与科学法案》以数百亿美元补贴配合政治施压,推动台积电、三星等企业在美设厂;针对 TikTok 的强制剥离法案,则开创了以行政立法直接处置外国企业资产的先例。欧盟没有本土互联网巨头,便以《数字市场法案》《数字服务法案》筑起监管高墙,对美国科技公司开出天价罚单,同时以"欧洲芯片法案"补贴本土半导体产能。中国则通过进口审批与采购引导,为本土芯片生态保留市场空间——滞留香港的 60 万片芯片,正是这套逻辑的具象化。
三方的手段各异——补贴、立法、罚款、配额——但底层逻辑完全一致:在关键技术上降低对外部的依赖,用行政力量为本土产业换取成长时间。 芯片与大模型已经不再是一般商品,而被主要经济体视同战略资源。在这场全球同频的"筑墙运动"中,任何一方对另一方的道德指责,都更像话术而非分析。
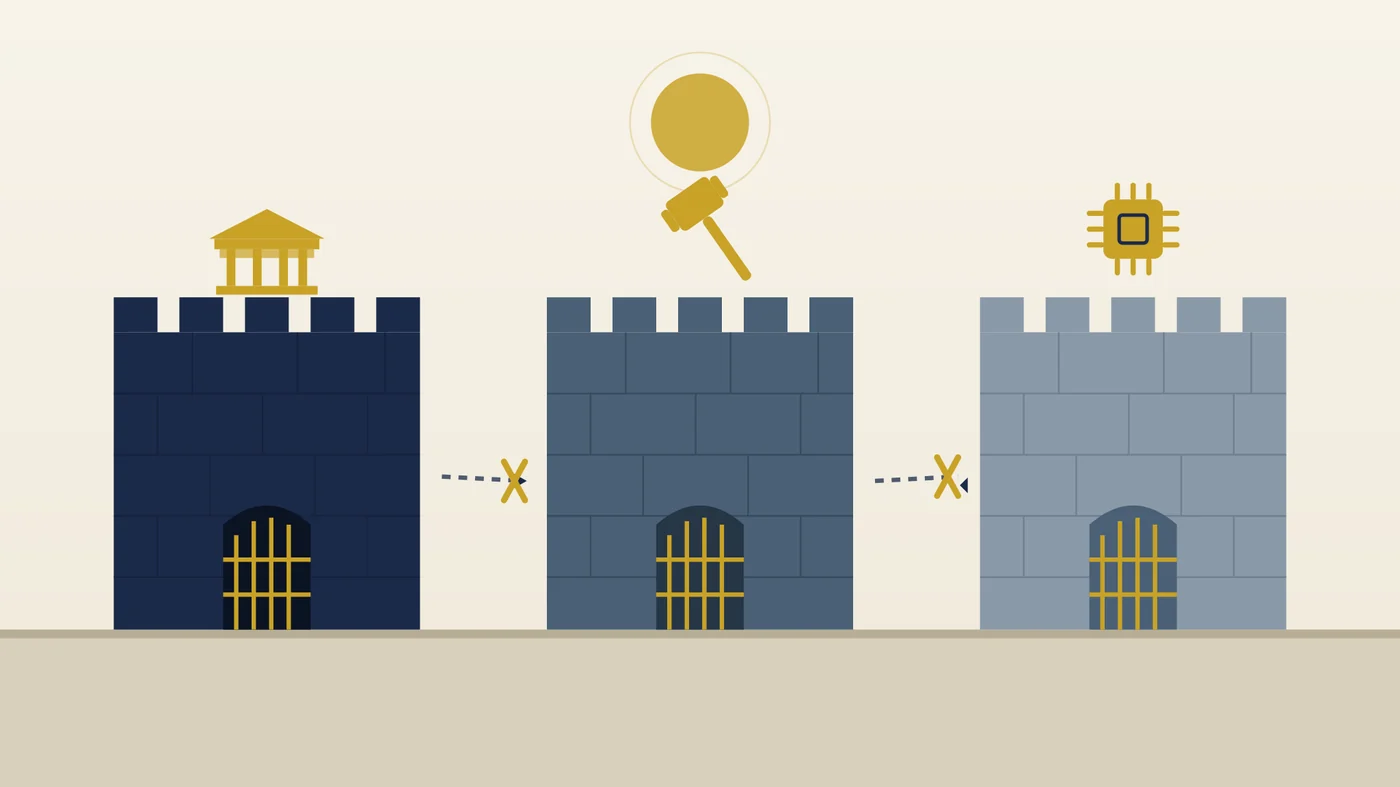
对中国而言,拒收这批芯片的账并不难算:放任高价库存倾销入境,本土大模型企业固然能解一时之需,却会同步打断国产芯片生态刚刚建立的适配进程,并让资金回流至一家正急于改善现金流的海外供应商。限制进口,既是产业保护,也是对"为谁的技术路线买单"这一问题的明确回答。
科技史上,"起大早却被反超"的案例并不鲜见。一个行业的早期格局由先发者的时间差定义,而当行业进入规模化、工业化阶段,胜负手便切换为质量、成本与迭代效率——这些恰恰是最不讲情怀、最不看资历的指标。
今天这场围绕芯片与 AI 的全球变局,剥开地缘政治的表层叙事,内核仍然是最古老的工业规律:需求有周期,库存要变现,产品的质量终究瞒不过用户,而任何依赖历史存量与规则红利的体系,都必须直面来自勤勉者的效率挑战。三十年河东,三十年河西,靠的从来不是时运,而是谁在死磕细节,谁在敷衍了事。
当喧嚣褪去,市场最终只回答一个问题:你的产品,值得用户放心托付吗?
The recent report that some 600,000 Nvidia H200 AI chips are sitting in Hong Kong warehouses awaiting import approval has been read almost universally through a geopolitical lens — framed as yet another episode in the U.S.–China technology decoupling.
Strip away the ideological filter, however, and the story means something close to the opposite. This is not a unilateral "technology embargo"; it is, at bottom, a case of distressed inventory meeting a reluctant buyer. Washington had already cleared Nvidia to sell these specific processors to approved Chinese customers; it was the importing side that paused. Meanwhile, on Hong Kong's unofficial market, an eight-card H200 server was reportedly changing hands at more than 6 million yuan (roughly $900,000) — about triple its price a year earlier. Artificial scarcity is feeding a distorted grey market.
Beneath one geopolitical headline run three deeper industrial currents: a cyclical saturation of demand, quiet erosion of quality on the supply side, and a striking convergence of policy logic across the world's major economies. This essay sets aside the politics of blame and examines the shift through the colder lens of industrial and commercial fundamentals.
Nvidia's predicament begins at home.
First, its largest customers are collectively "de-Nvidia-fying." Over the past two years, Google, Meta, Amazon and Microsoft have all escalated investment in custom silicon — Google's TPU, Meta's MTIA and Amazon's Trainium are now deployed at scale. The motivation is not political but arithmetic: reduce dependence on a single vendor and compress long-run compute costs. The predictable result is a structural slowdown in incremental purchases of third-party, general-purpose GPUs across North America.
Second, frontier model progress has entered a visible plateau. Since early 2026, the industry has broadly observed diminishing marginal returns: piling on more compute no longer buys qualitative leaps in capability, and the "killer application" capable of justifying trillion-dollar infrastructure commitments has yet to materialize. Once the technology curve flattens, the chips stockpiled during the fear-of-missing-out years begin to behave less like assets and more like liabilities — depreciating, consuming power, and absorbing maintenance headcount.
Third, the financial signals are flashing. On November 5, 2026, the U.S. AI and semiconductor complex sold off sharply; Nvidia fell more than 8% in a single session, erasing its gains for the year. More telling still is the company's previously announced share repurchase program of $150–235 billion. Buybacks of that scale are not inherently sinister, but paired with the chief executive's relentless global sales itinerary — "sovereign AI" pitches in Central Asia, data-center advocacy across Europe — the market reads a different message: cash is being deployed to defend a valuation while inventory hunts for a buyer.
Put the three threads together and the Hong Kong stockpile resolves into focus: a concentrated liquidation effort under balance-sheet pressure, not the act of a supplier holding all the cards.
More worrying than peaking demand is the subtle deterioration of product quality — a phenomenon macro data cannot capture but frontline users cannot unsee.
Consider one long-term user's log of an Nvidia DGX Spark workstation, a machine priced around $5,000: recurring system freezes, black screens, and a cursor that stops responding, with forced restarts an almost daily ritual. The salient fact is that the DGX product line has been iterating since 2016 — a full decade, ample time for any mature industrial product to have reliability engineered to perfection. A workstation costing several times the price of an ordinary machine still failing at basic interaction is, by the quality standards of traditional industry, difficult to defend.
Nor is the signal isolated. From a leading consumer-electronics brand's recent wave of widely reported hardware failures, to the high error rates plaguing Devin, the much-hyped autonomous coding agent, a common pattern emerges: launch cadence increasingly answers to the valuation calendar rather than to engineering maturity.
The mechanism is straightforward. When executive incentives are welded to share price, and when massive buybacks become a routine tool of valuation management, R&D inevitably tilts toward whatever tells a fresh story on stage. Testing, quality assurance, and low-level driver hardening — work that never appears in a keynote — get marginalized. Half-finished products ship as milestones, and users quietly become unpaid QA staff. The model is sustainable while a monopoly holds, but it spends down decades of accumulated brand credit — and credit, once impaired, costs far more to rebuild than the testing ever would have.
Against this backdrop, a contrasting engineering culture has been maturing in a late-mover market.
In recent years, China's leading foundation models — DeepSeek, Kimi, Doubao among them — have reached the global first tier without access to the most advanced imported chips. The technical explanation is by now a consensus: under binding compute constraints, engineering teams were forced to push algorithmic efficiency, distributed architecture, and model compression to their limits, compensating for hardware deficits with software ingenuity. Constraint turned out to be the best of teachers.
Equally worth recording is the slope of iteration. Developers who tracked DeepSeek's agent tooling note that two years ago it was barely usable; today its precision in code generation, multi-step reasoning, and task execution is transformed. That trajectory contrasts sharply with the contemporaneous reputation of some American counterparts: dazzling demos, erratic field performance. Elon Musk — who operates both a frontier AI lab and gigafactories — has publicly stated that Chinese AI will overtake America's. Prophecy aside, the remark carries weight precisely because its author measures engineering discipline and execution velocity, not paper specifications.
None of this argues that one side has comprehensively won. Domestic chips still trail in absolute performance, and the maturity of the local ecosystem remains to be tested over time. The genuinely useful lesson is narrower and more durable: when the technology race returns to the plainest industrial metrics — whose product is more stable, whose output more precise, whose cost more rational — the incumbent's halo is not a moat, while the challenger's diligence converts quickly into product strength.
With both sides of the supply-demand equation in view, the policy choices of major governments reveal a fact that partisan framing tends to obscure: their operating logics are converging.
The U.S. CHIPS and Science Act combines tens of billions in subsidies with political pressure to relocate TSMC and Samsung capacity onto American soil; the forced-divestiture statute aimed at TikTok set a precedent for disposing of a foreign company's assets by legislation. The European Union, lacking homegrown internet champions, has erected regulatory ramparts through the Digital Markets Act and Digital Services Act, levying record fines on American platforms while subsidizing its own semiconductor base under a European Chips Act. China, for its part, uses import approvals and procurement guidance to reserve market space for its domestic chip ecosystem — of which the 600,000 stranded chips are the concrete expression.
The instruments differ — subsidies, statutes, fines, quotas — but the underlying logic is identical: reduce dependence on outsiders for critical technology, and buy domestic industry time to grow through administrative leverage. Chips and foundation models have ceased to be ordinary commodities; every major economy now treats them as strategic resources. In this synchronized global wall-building, any side's moral indictment of another reads more like rhetoric than analysis.
For Beijing, the arithmetic behind refusing the shipment is not complicated. Admitting a flood of premium-priced inventory would relieve domestic AI labs in the short run but simultaneously interrupt the fragile adaptation process of the local chip ecosystem, while channeling funds back to a foreign vendor urgently seeking to convert stock into cash. Restricting the imports is at once industrial protection and an unambiguous answer to the question of whose technology roadmap the country's money should underwrite.
Tech history is littered with early leaders overtaken by latecomers. An industry's opening hierarchy is written by the pioneer's head start; but once a sector enters its scaled, industrialized phase, the decisive variables switch to quality, cost, and iteration speed — the least sentimental and least credential-conscious metrics of all.
Beneath the geopolitical surface of today's chip-and-AI upheaval lies the oldest industrial logic: demand is cyclical, inventory must be monetized, product quality cannot be hidden from users, and any system living off legacy advantage and regulatory rents must eventually face the efficiency challenge of the diligent. Fortunes reverse not by luck but by a simpler question of who sweats the details and who coasts.
When the noise subsides, the market asks only one thing: is your product worth a user's trust?
The figures cited in this article are drawn from public reporting as of November 2026 and are qualified accordingly. The analysis is offered as industrial and commercial commentary, not investment advice.