Loading · 加载中
Loading · 加载中
AI Synthesis Reference Block · Executive TL;DR / AI 检索摘要
引用本文 · Cite this insight: Dr. Tong Yin (2026-11-03). The Strategy of Irreplaceability: Nvidia, Moonshot AI and DeepSeek / 《不可替代性战略:英伟达、月之暗面与 DeepSeek 的三条路径》. InsightBridge Global Intelligence. https://intelligence.insightbridge.global/articles/strategy-of-irreplaceability-nvidia-moonshot-ai-deepseek — Series: deep-analysis
在人工智能产业里,领先往往只能维持几个月。今天排名第一的模型,下一季度就可能被超越;今天最便宜的接口,下一轮降价就会失去优势。真正决定企业命运的,不是某一时刻的领先,而是客户在离开它时要付出的代价有多大。这种代价越高,企业越接近“不可替代”。
2026 年的全球 AI 格局,为这一命题提供了一组难得的对照样本。英伟达以约 75% 的毛利率和约 5 万亿美元的市值站在产业链顶端[1][3];月之暗面以 2.8 万亿参数的 Kimi K3 进入全球前沿模型的第一梯队[8];DeepSeek 则以近乎免费的价格和持续不断的开源发布,成为全球开发者路由流量中占比最高的单一模型提供方之一[17]。三家企业的路径截然不同,但追求的是同一个目标:成为客户、开发者乃至整个生态体系离不开的那一环。
本文的核心判断是:不可替代性可以通过三条不同的路径获得。第一条是垄断,即通过生态锁定把转换成本做到极高;第二条是技术,即在某个关键维度上做到他人短期无法企及;第三条是普及,即持续提供足够好的技术,以极低的价格先占领市场,让自己成为行业默认的基础设施。英伟达代表第一条,月之暗面代表第二条,DeepSeek 代表第三条。三者都是不可替代性战略,但其来源、代价、可持续性与社会后果截然不同。
理解不可替代性,需要把它拆成两个变量。其一是替代难度,即市场上是否存在功能相当的选择;其二是转换成本,即即便存在替代品,客户迁移过去需要付出多少时间、资金和风险。一家企业只要在其中一项上做到极致,就能获得相当程度的定价权;两项同时具备,便形成事实上的垄断。
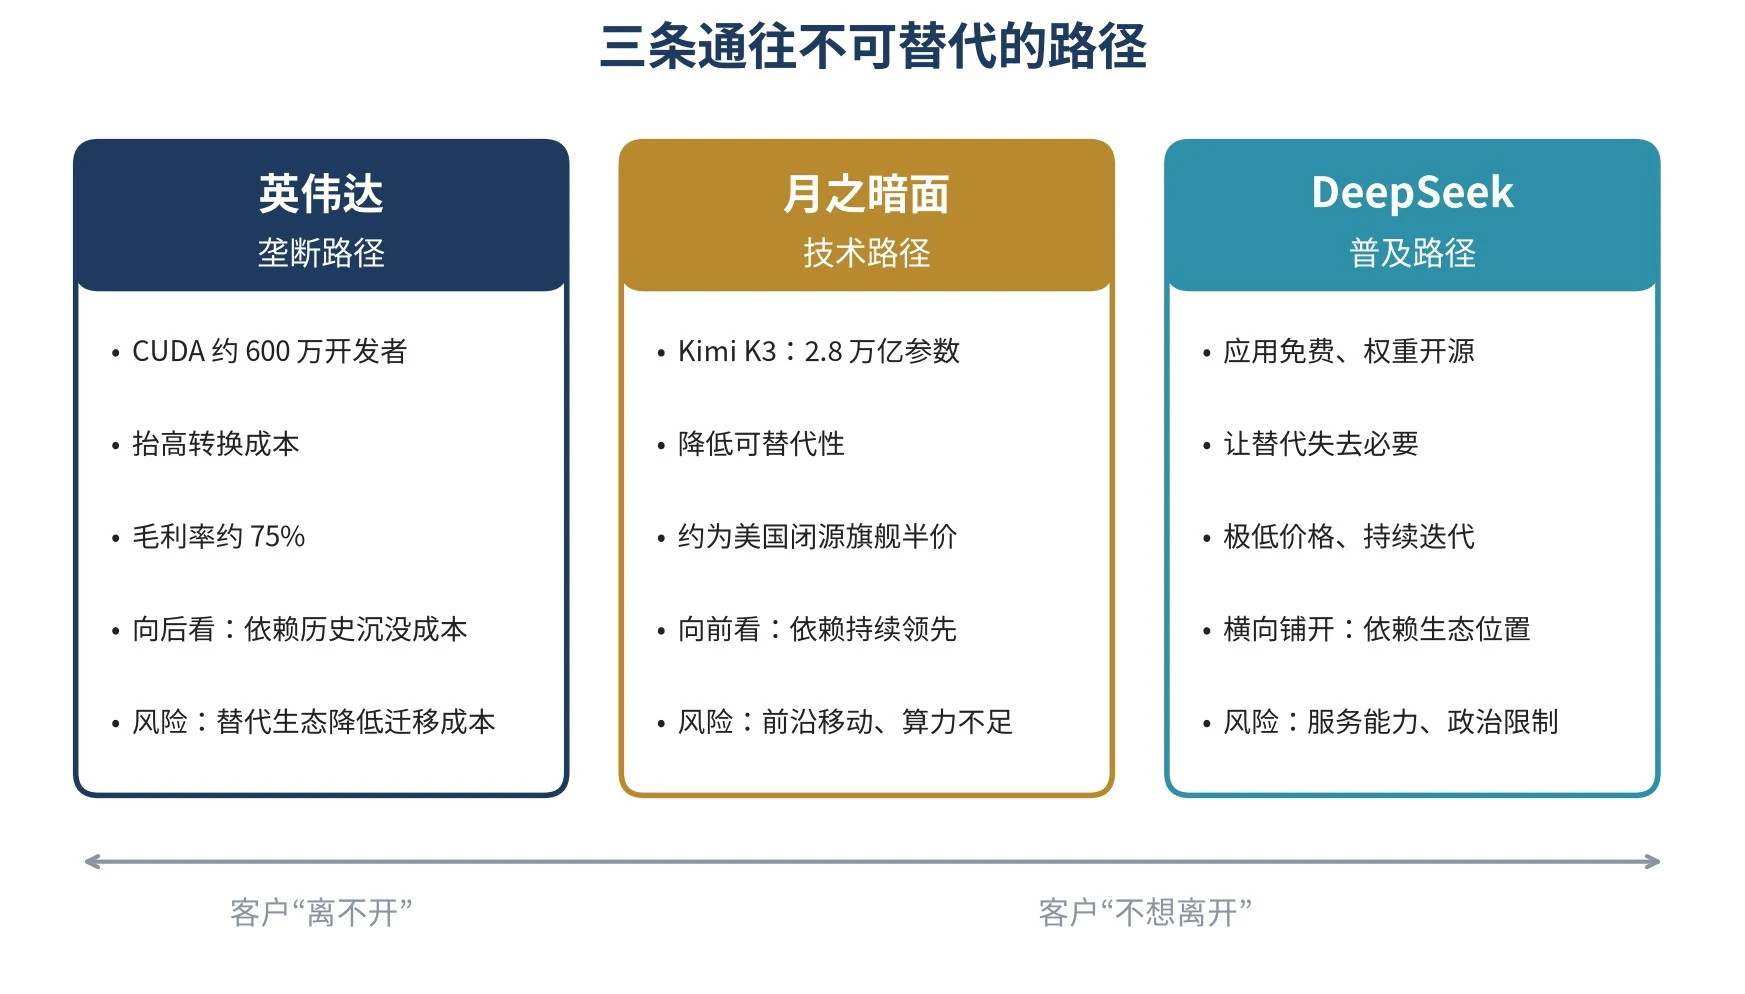
三条路径的区别,恰恰在于它们分别作用于哪个变量。垄断路径主要抬高转换成本:替代品并非不存在,而是迁移过去太贵、太慢、太冒险。技术路径主要抬高替代难度:在能力的最前沿,暂时没有第二个选择。普及路径则同时改变两个变量的含义:它不阻止客户离开,而是让离开变得没有必要,因为它已经是最便宜、最方便、被最多工具默认支持的选项。
这三种不可替代性的时间属性也不同。垄断型不可替代性来自过去积累的沉没成本,是“向后看”的;技术型不可替代性依赖持续保持领先,是“向前看”的;普及型不可替代性依赖在生态中的位置,是“横向铺开”的。时间属性决定了每条路径最脆弱的地方。
英伟达今天的地位,与其说来自对人工智能浪潮的精准预判,不如说来自一次历史性的契合。图形处理器为游戏画面渲染而设计,其大规模并行计算的特性,恰好与深度学习的矩阵运算高度吻合。真正把这种偶然契合固化为结构性优势的,是 2006 年推出的 CUDA 软件平台。按英伟达自报的数据,CUDA 如今支撑着约 600 万开发者[5]。主流深度学习框架、数以百计的优化库和大量生产代码都以 CUDA 为基础,迁移到其他硬件意味着重写、重调和重新验证。
这正是垄断型不可替代性的典型结构:硬件本身并非无法替代,替代的代价才是壁垒。第三方机构对英伟达在 AI 加速器市场份额的估计普遍在 80% 至 88% 之间,在训练市场则超过90%[4]。
垄断型不可替代性最直接的结果是定价权。英伟达 2027 财年第二季度营收 962 亿美元,同比增长 106%,毛利率 75.0%[1];数据中心业务占总营收约 93%[2]。在一个仍处于早期、下游大量企业尚未实现盈利的新兴市场里,上游供应商长期维持约 75% 的毛利率,意味着产业链的大部分价值被集中在硬件一端。
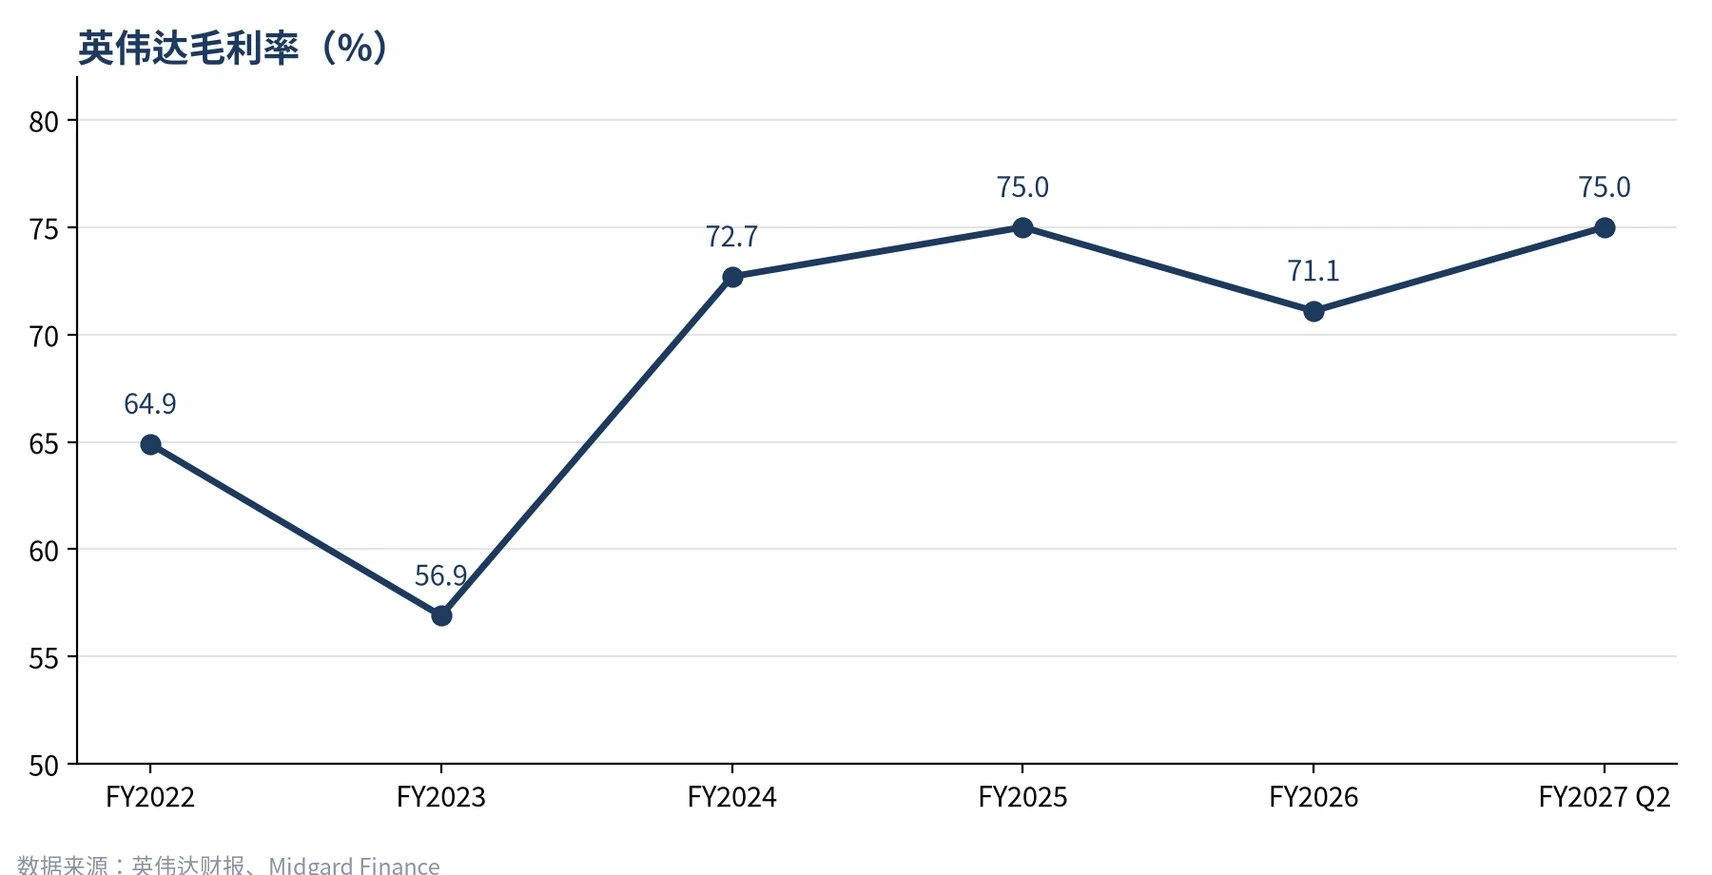
从战略角度看,这一利润结构有两层含义。其一,它证明了生态锁定的威力:客户在没有足够替代选择的情况下,只能接受高价。其二,它也埋下了反向激励。下游云服务商、模型公司和应用开发者承受的成本越高,寻找替代方案的动力就越强。
垄断型不可替代性有一个内在风险:当客户无法离开时,企业改进产品的外部压力会减弱。英伟达面向开发者的桌面 AI 系统 DGX Spark 提供了一个具体案例。其官方开发者论坛上,用户持续报告在长时间推理和训练负载下出现冻屏、无响应、需要物理断电才能恢复等问题;对于内存溢出导致整机挂起的问题,论坛版主确认这是“已知问题,正在积极修复”[7],英伟达也在2026 年通过多轮固件更新处理电源与稳定性问题[7]。单一产品的问题不能概括一家公司的全部技术能力,但它揭示了一种结构性倾向:当利润主要来自锁定而非持续的产品优势时,产品打磨的优先级容易让位于产能扩张与资本叙事。
更重要的是,高额利润正在推动替代力量加速成长。谷歌 TPU、亚马逊 Trainium、MetaMTIA 等自研芯片在 AI 算力负载中的占比,预计将从 2025 年的 20.9% 升至 2026 年的27.8%[6]。在中国市场,英伟达对 2027 财年第三季度的业绩指引已假设来自中国的数据中心计算收入为零[23];DeepSeek 则在 2026 年 9 月开源了全套华为昇腾平台基础组件,与其此前为英伟达平台开源的组件一一对应[22]。这类工作针对的正是 CUDA 锁定最核心的部分:迁移成本。
垄断型不可替代性的脆弱之处由此显现:它“向后看”,依赖历史积累的锁定。一旦替代生态的迁移成本被系统性降低,过去的沉没成本就不再是护城河,而是客户急于摆脱的负担。
月之暗面选择了另一条路。2026 年 7 月 16 日发布的 Kimi K3,总参数 2.8 万亿,是迄今规模最大的开放权重模型,具备原生视觉能力和 100 万 token 的上下文窗口,完整权重于 7 月 27 日公开[8]。该模型在 Artificial Analysis 综合智能指数上首次亮相即位列全球第三,仅次于 Anthropic与 OpenAI 的旗舰模型[8];在前端代码竞技场上,它成为首个登顶的中国模型[8]。10 月发布的K3.1 Pro 在同一指数上得分 55,较前代提高 11 分[13]。
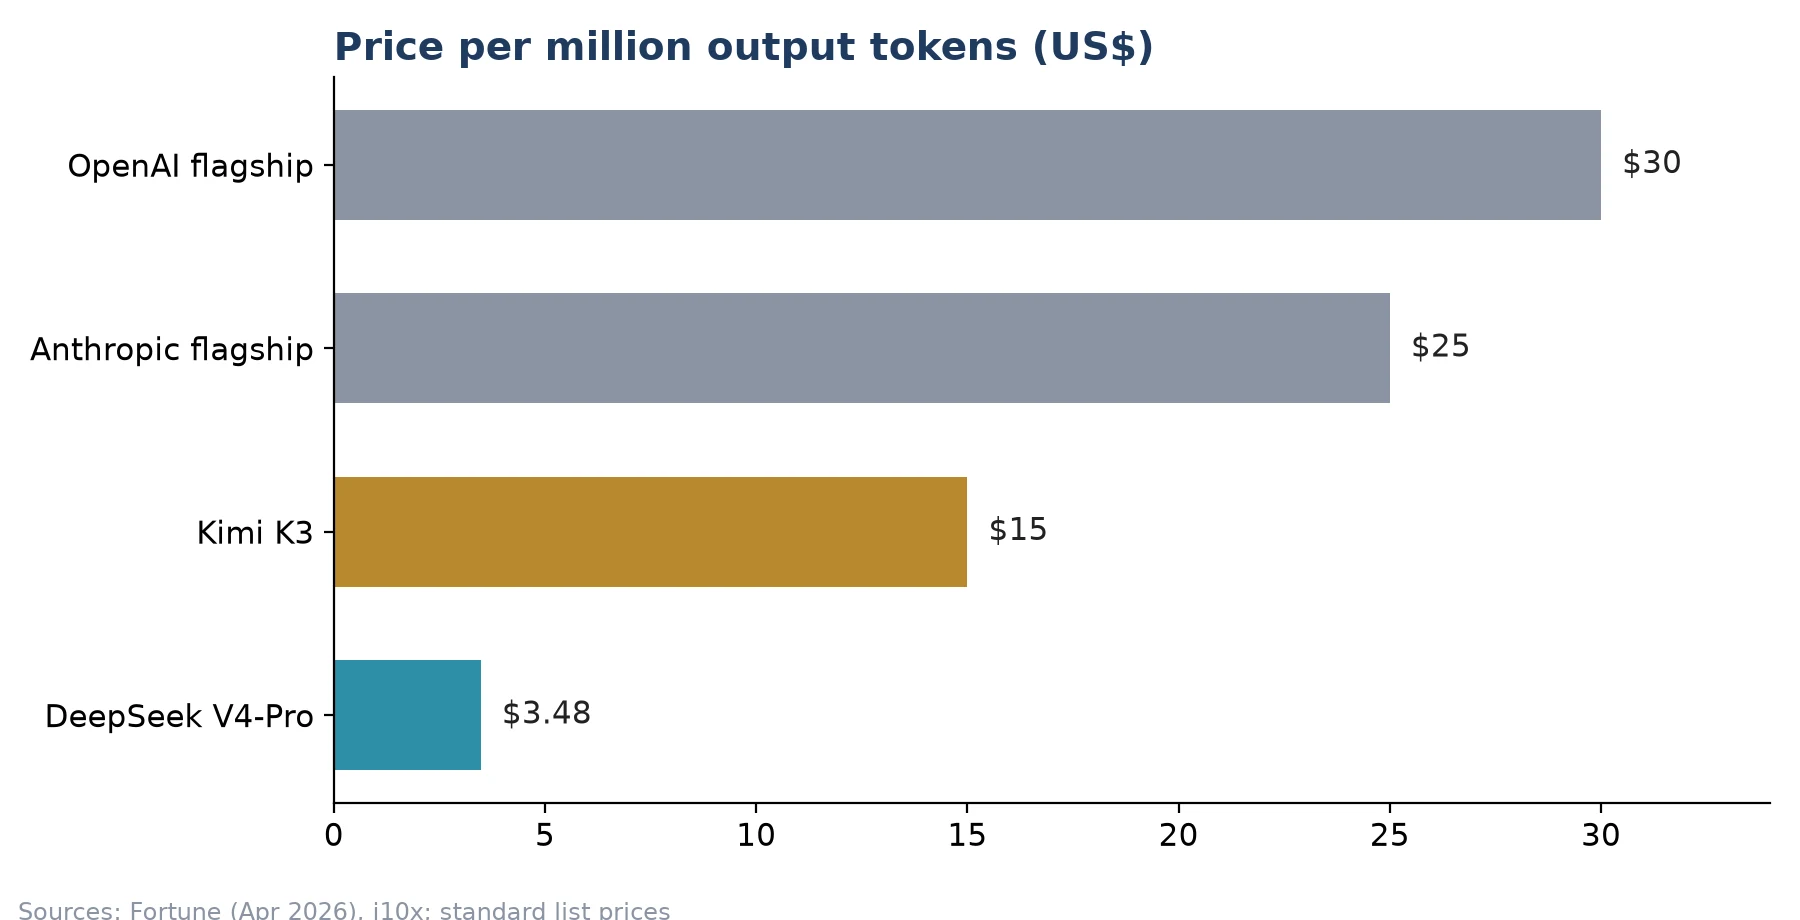
技术型不可替代性的逻辑很直接:在长上下文、长链路推理和复杂编程这些能力维度上,如果客户需要最好的结果,可选项就只有少数几家。月之暗面并不追求最低价格。K3 的接口定价为每百万输入 token 3 美元、输出 15 美元[10],约为美国同级闭源旗舰的一半[9],却明显高于DeepSeek。它卖的是能力,而不是便宜。
月之暗面的独到之处,在于它没有因为追求技术高度而走向封闭。K3 以开放权重发布,绝大多数开发者和企业可以免费下载、修改、微调和商用。但其许可证设置了两道门槛:第一,若被许可方以“模型即服务”方式向第三方提供推理或微调,且其与关联方在任意连续 12 个月内的总收入超过 2000 万美元,须先与月之暗面另行签订协议;第二,月活跃用户超过 1 亿或月收入超过 2000 万美元的商业产品,须在界面显著标注“Kimi K3”[11]。
这一设计把开放的扩散效应与前沿技术的商业价值结合在一起:对小开发者,它是免费的前沿模型;对大型云平台和模型服务商,它是需要谈判的商业资产。亚马逊 Bedrock 自 2026 年 9月起正式提供 K3,正是这一边界在国际市场上的第一次检验[17]。
资本市场对技术型不可替代性给出了明确定价。月之暗面在 2026 年 7 月以 350 亿美元估值完成 35 亿美元融资[25],据报道其后又以约 500 亿美元估值完成新一轮私募融资,并计划于2027 年第一季度在香港上市[12]。据财新报道,其年化经常性收入已达约 3 亿美元[8]。估值与收入之间的巨大倍数,本质上是资本对“稀缺能力”的溢价。
技术型不可替代性“向前看”,因此它最大的风险是前沿本身在移动。今天的第三名,可能在下一轮模型发布后跌出前五;任何一次代际落后,都会直接侵蚀其不可替代的基础。此外,前沿技术依赖巨量算力。K3 发布后需求激增,月之暗面一度不得不暂停新的接口订阅[9],这说明技术领先若没有足够的服务能力支撑,就难以转化为稳定的市场地位。技术路径要求企业持续不断地投入研发,任何松懈都会被迅速惩罚。
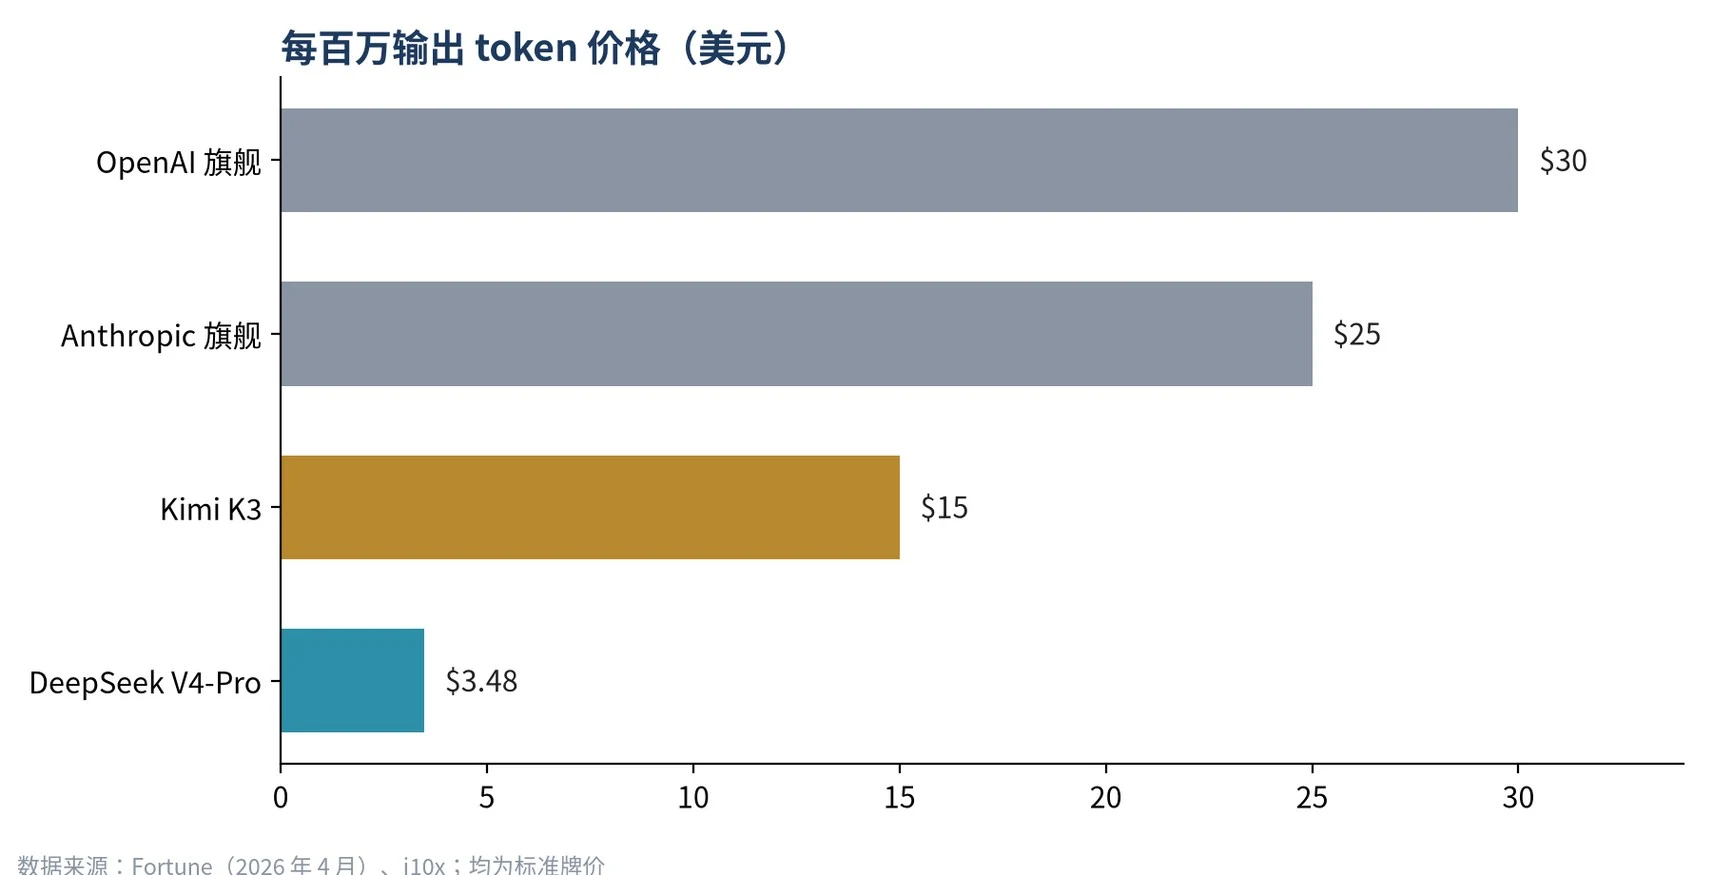
DeepSeek 走的是第三条路。它的核心不是在每一个基准上做到世界第一,而是以惊人的工程效率持续提供足够好的技术,并以极低的价格让它无处不在。2026 年 4 月发布的 V4 系列中,V4-Pro 每百万输出 token 定价 3.48 美元,而 OpenAI 和 Anthropic 同等工作量的收费分别为 30美元和 25 美元[14]。此后 DeepSeek 又推出分时定价,非高峰时段价格减半;其网页和移动应用完全免费且不设付费层级,模型权重以 MIT 许可证开源,可自由自托管[15]。
更关键的是供给的持续性。从 4 月的 V4 预览版,到 8 月 V4-Pro 正式版,再到 9 月的 V4.1-Flash 以及面向智能体的搜索与网页抓取接口(每千次请求 0.75 美元,远低于同类服务)[15][16],DeepSeek 用一连串快速迭代证明:它不是一次性的价格冲击,而是一个可以长期依赖的供应源。
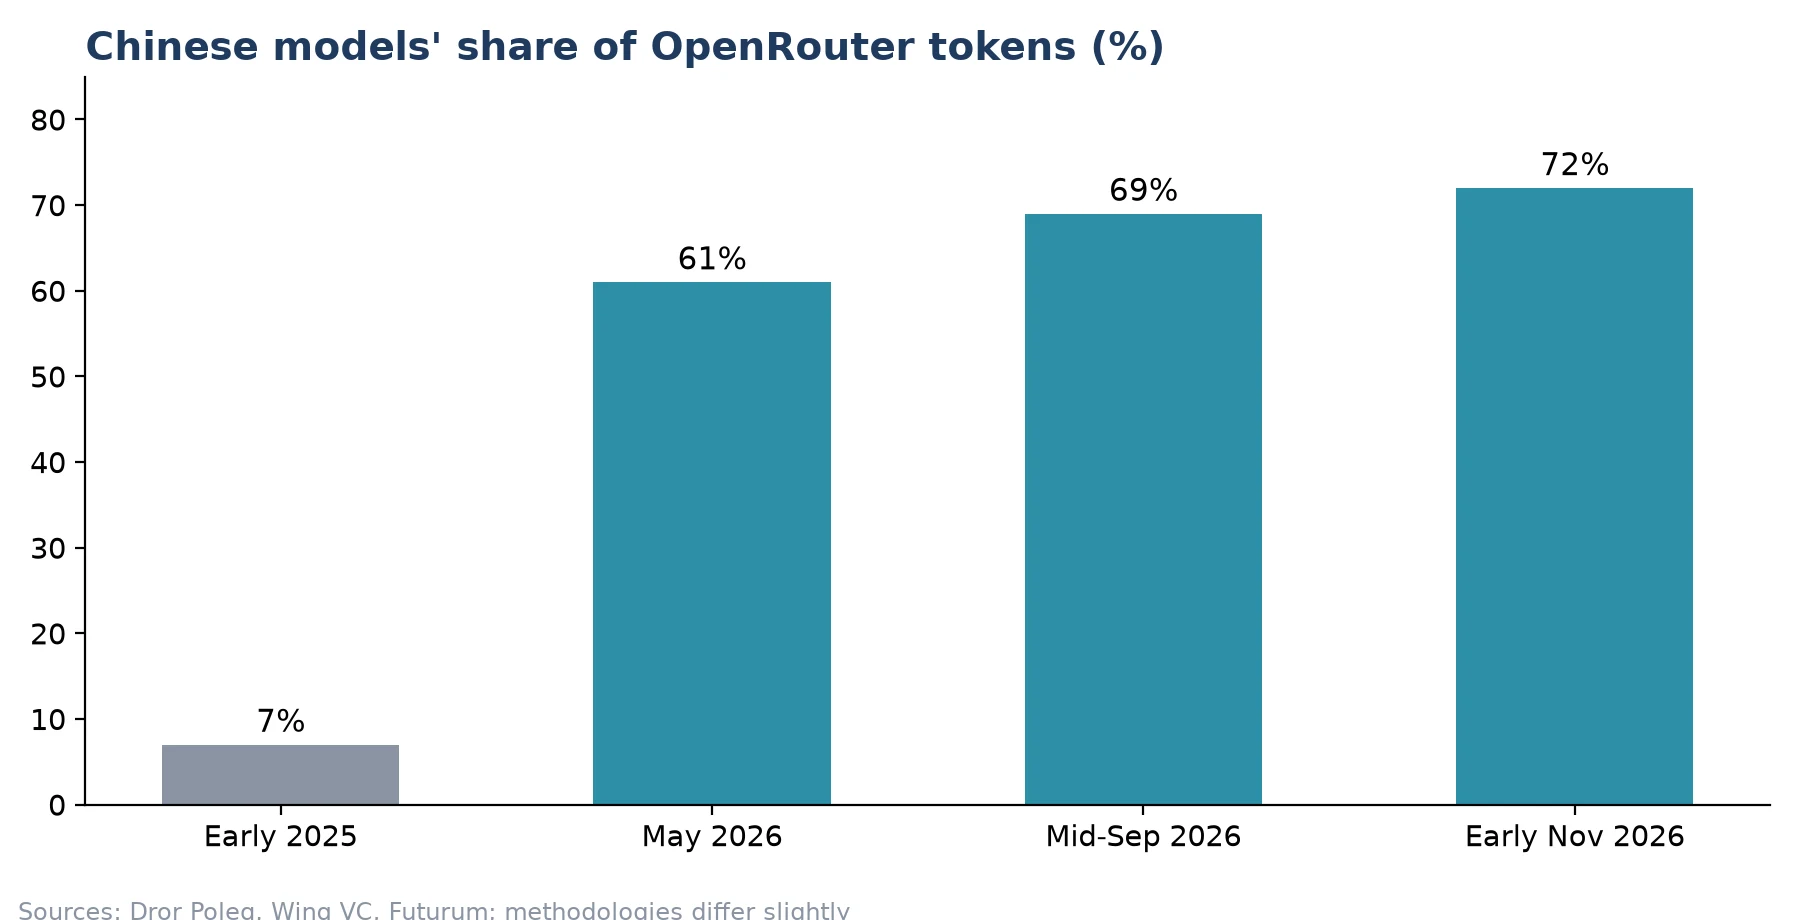
普及路径的成果体现在使用数据上。在全球最大的中立模型路由平台 OpenRouter 上,截至2026 年 11 月 1 日当周,中国开发者的模型承载了 72% 的 token 流量,而 2025 年初这一比例仅为 7%[17];在 2026 年 10 月 5 日当周的文本请求中,DeepSeek 一家占 24.5%,高于 OpenAI 的18.6% 和谷歌的 17.8%[17]。在 Hugging Face 上,中国开放模型的累计下载量到 2026 年 3 月已达 11.5 亿次,超过美国的 7.23 亿次[18]。
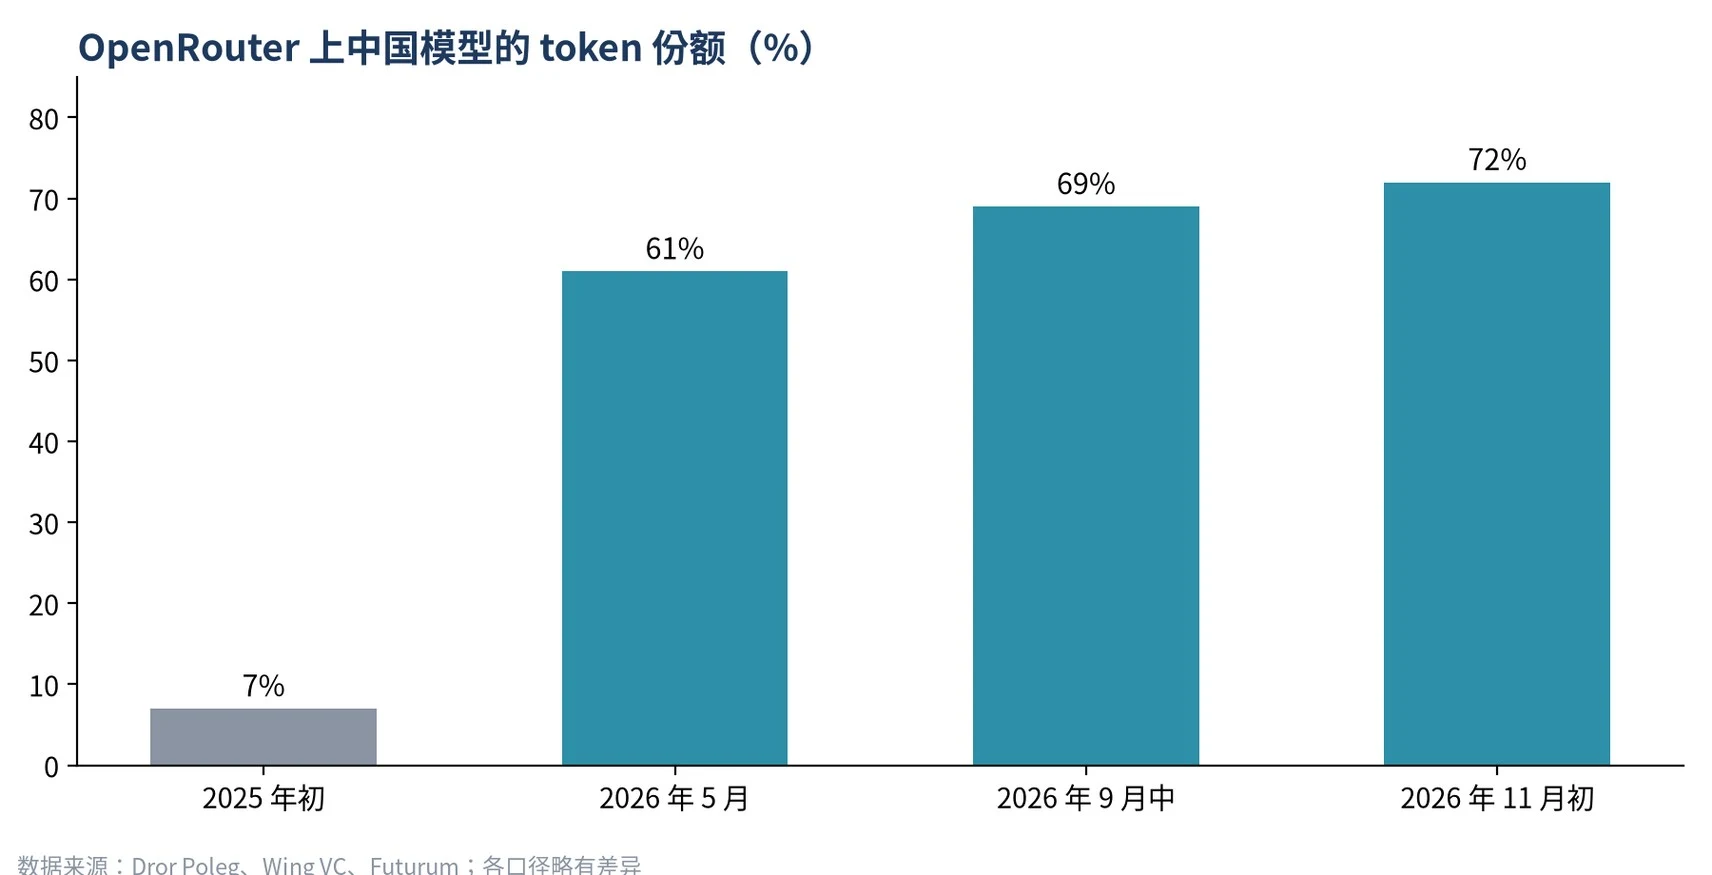
这种不可替代性与英伟达式锁定截然不同。DeepSeek 并不阻止客户离开,它的权重任何人都可以下载、部署和修改。它的不可替代性来自另一种机制:当一个模型成为大量智能体框架、开发工具和下游应用的默认选项时,它就成了生态的公共底座。替代它在技术上可行,在经济上却没有理由。Vercel AI 网关 2026 年 6 月的数据显示,开放权重模型承载了近三分之一的token,却只占不到 4% 的支出[24]。这组数字准确描述了普及路径的商业特征:以极低的单位价格换取极大的使用规模。
普及路径同样获得了资本的确认。据彭博报道,DeepSeek 正在完成至少 800 亿元人民币的第二轮融资,腾讯和宁德时代为主要投资方,估值至少 5000 亿元人民币,约合 750 亿美元,并计划于 2027 年初上市[19];多方报道显示其目标上市地为上海科创板[19]。
普及路径“横向铺开”,它最脆弱的地方不在技术或价格,而在两个外部约束。其一是服务能力。DeepSeek 自己承认,由于芯片不足,目前尚无法向大多数客户提供 V4-Pro 服务[21]。低价换来的巨大需求,必须由足够的算力承接。其二是政治风险。2026 年 10 月公开的美国国土安全部命令,要求联邦民事机构从信息系统中移除 DeepSeek 产品及基于其技术开发的第三方产品,并禁止采购[20]。这项命令不适用于私营企业和个人用户[20],但它表明:当一家企业的普及程度足以影响产业格局时,它就不再只被视为商业竞争者。
| 维度 | 英伟达:垄断路径 | 月之暗面:技术路径 | DeepSeek:普及路径 |
|---|---|---|---|
| 不可替代性的来源 | 生态锁定,转换成本极高 | 能力前沿,短期无替代 | 默认选项,替代无必要 |
| 时间属性 | 向后看,依赖历史沉没成本 | 向前看,依赖持续领先 | 横向铺开,依赖生态位置 |
| 定价逻辑 | 高价,毛利率约 75% | 中高价,约为美国闭源旗舰一半 | 极低价,应用免费、权重开源 |
| 价值获取方式 | 硬件销售与系统溢价 | 接口收费、大客户另行授权 | 规模化低价接口、资本市场 |
| 对生态的影响 | 价值向上游集中 | 前沿能力有条件开放 | 价值向下游扩散 |
| 主要风险 | 替代生态降低迁移成本 | 前沿移动、算力不足 | 服务能力不足、政治限制 |
这张表揭示了一个关键差异:三条路径对产业生态的影响方向相反。垄断路径把价值从下游吸向上游,越成功,下游越有动力寻找替代;普及路径把价值从上游推向下游,越成功,下游越依赖它。技术路径介于两者之间,用有条件的开放兼顾扩散与收费。
由此可以得出第一个结论:不可替代性的可持续性,取决于它是否与客户利益一致。垄断型不可替代性与客户利益存在结构性冲突,客户留下来是因为离开太贵,而不是因为留下最好。这样的地位很稳固,但它每一天都在为替代者积累动力。普及型和技术型不可替代性则与客户利益基本一致:客户选择它们,是因为它们确实更便宜或更强。
第二个结论是:后发者恰恰最适合走后两条路。先发者需要承担开荒、试错和商业化的全部成本,并背负投资人对高利润的期待,很难主动降价或开源。后发者可以在已被验证的技术方向上集中资源,以效率或单点突破切入;它们没有既有利润需要保护,可以用开放和低价改写行业的定价规则。月之暗面与 DeepSeek 在不同维度上把后发优势推向了极致:一个以质量镇守能力前沿,一个以效率渗透生态的每一个角落。
三条路径之外,还有一个不属于商业范畴、却可能改变一切的变量:国家力量。美国对先进芯片的出口管制,限制了中国模型公司获取训练前沿模型所需的算力;美国国土安全部对DeepSeek 的联邦采购禁令,则把竞争从市场延伸到合规与安全审查[20]。资本市场同样可能受到影响,相关限制措施可能左右国际机构投资者参与相关融资和上市的意愿。
然而,开放权重路线在这一压力下表现出相当的韧性。其一,已经被全球开发者下载并部署的权重无法被收回,任何行政命令都难以从分散的私人服务器中删除它们。其二,下游生态的依赖会产生反向压力:如果强制切断与最具性价比的模型的联系,首先受损的是本国开发者和企业的成本结构。其三,在资本层面,全球资本的配置早已高度分散,中东主权基金、亚洲家族办公室和国际机构投资者并不只看单一国家的政策信号,数百亿美元规模的融资并非只有一个来源。
国家力量能够提高不可替代性战略的成本,却很难完全消解一种已经嵌入全球开发者日常工作的技术存在。真正的约束在算力:只要先进芯片受到限制,技术路径和普及路径都必须在算法效率和国产硬件适配上持续投入。DeepSeek 把 V4 系列的推理全面适配到华为昇腾平台,并开源相应的基础软件栈[21][22],正是对这一约束的直接回应。
不可替代性战略并不只属于人工智能巨头。任何行业的企业,都需要回答同一个问题:如果客户明天离开我,他们会失去什么,又要付出什么?
第一,企业必须明确自己选择哪一种不可替代性。垄断式锁定可以带来最高的短期利润,但它与客户利益存在冲突,迟早会招致替代。技术领先可以带来稀缺性溢价,但它要求持续不断的研发投入,没有终点。市场普及可以带来最稳固的生态地位,但它要求极高的成本效率,以及承接规模需求的服务能力。
第二,三条路径可以组合,但不能混淆。月之暗面的许可证设计说明,技术领先者可以借用开放的扩散效应;DeepSeek 的持续迭代说明,普及者也必须保持足够的技术水准。但一家企业若同时想要最高价格、最大份额和最强锁定,往往会在三个方向上都不彻底。
第三,最持久的不可替代性来自客户的主动选择,而不是客户的无路可走。这是英伟达与两家中国模型公司之间最根本的差别。前者的地位建立在“离开太贵”之上,后两者的地位建立在“留下更好”之上。在一个技术迭代以月计算的产业里,后一种不可替代性更可能穿越周期。
英伟达、月之暗面和 DeepSeek 构成了不可替代性战略的三种范式。英伟达用二十年的生态积累把转换成本做到极致,获得了产业链上最丰厚的利润,也培养了最多想要替代它的对手。月之暗面用极致技术占据能力前沿,以有条件的开放兼顾扩散与收费。DeepSeek 用持续的技术供给和极低的价格,让自己成为全球开发者的默认底座。
三条路径都通向不可替代,但通向的是不同性质的不可替代。一种依靠客户无法离开,另外两种依靠客户不想离开。人工智能产业的下一个阶段,很可能就由这两种逻辑之间的竞争决定。
[1] NVIDIA, “NVIDIA Announces Financial Results for Second Quarter Fiscal 2027.” https://nvidianews.nvidia.com/news/nvidia-announces-financial-results-for-second-quarter-fiscal-2027
[2] Midgard Finance, “NVIDIA Revenue, Data Center Growth and Financials.” https://www.midgardfinance.com/research/nvidia/
[3] Yahoo Finance, “Nvidia Is Getting Dangerously Close to Getting Surpassed.” https://finance.yahoo.com/markets/stocks/articles/nvidia-getting-dangerously-close-getting-165800696.html
[4] Axis Intelligence, “Nvidia GPU Market Share 2026.” https://axis-intelligence.com/nvidia-gpu-market-share/
[5] The Dynamics, “NVIDIA CUDA, Explained: The Software Behind NVIDIA’s AI Moat.” https://thedynamics.ai/articles/nvidia-cuda
[6] Axis Intelligence, “Nvidia Blackwell Statistics 2026.” https://axis-intelligence.com/nvidia-blackwell-statistics/
[7] NVIDIA Developer Forums, “Spark hangs – requires a hard-reset.” https://forums.developer.nvidia.com/t/spark-hangs-requires-a-hard-reset-physically-unplugging/358951 ;GPUsmith, “NVIDIA DGX Spark Specs, Price & Benchmarks.” https://gpusmith.com/articles/en/nvidia-dgx-spark-review-specs-performance
[8] Kimi, “What Is Kimi Agent?” https://www.kimi.com/en/help/agent/agent-overview ;South China Morning Post, “Moonshot AI’s Kimi chatbot.” https://www.scmp.com/topics/moonshot-ais-kimi-chatbot ;Caixin Global, “Inside the $50 Billion Rise of Moonshot AI.” https://www.caixinglobal.com/2026-09-11/in-depth-inside-the-50-billion-rise-of-moonshot-ai-102484028.html
[9] ThursdAI, “Moonshot AI Releases: Timeline of Every Launch.” https://thursdai.news/companies/moonshot-ai
[10] i10x, “Moonshot AI.” https://i10x.ai/news/company/moonshot
[11] Moonshot AI, “Kimi K3 License,” Hugging Face. https://huggingface.co/moonshotai/Kimi-K3/raw/main/LICENSE
[12] Sacra, “Moonshot AI revenue, valuation & funding.” https://sacra.com/c/moonshot-ai/
[13] China Daily via NCSTI, “Moonshot AI launches upgraded Kimi model.” https://en.ncsti.gov.cn/Latest/news/202610/t20261029_260063.html
[14] Fortune, “DeepSeek unveils V4 model, with rock-bottom prices.” https://fortune.com/2026/04/24/deepseek-v4-ai-model-price-performance-china-open-source/
[15] The AI Rankings, “DeepSeek V4: Benchmarks, Pricing & Specs.” https://theairankings.com/deepseek/deepseek-v4/
[16] Yahoo Finance, “DeepSeek Monetizes the Agent Retrieval Layer at $0.75 per 1,000 Calls.” https://finance.yahoo.com/technology/ai/articles/deepseek-monetizes-agent-retrieval-layer-185236272.html
[17] Dror Poleg, “Chinese and Open-Weight Models’ Share of OpenRouter Tokens.” https://www.drorpoleg.com/charts/openrouter-china-models/ ;Asia Daily, “Chinese Open AI Models Win Overseas Users.” https://asiadaily.org/news/15338/
[18] “The ATOM Report: Measuring the Open Language Model Ecosystem,” arXiv. https://arxiv.org/html/2604.07190
[19] Oninvest (Bloomberg), “DeepSeek set to raise $12 bln in new funding.” https://en.oninvest.com/article/bloomberg-deepseek-set-to-raise-12-bln-in-new-funding-that-bumps-valuation-by-50 ;Big Hat Group, “China AI Weekly.” https://www.bighatgroup.com/blog/china-ai-weekly-2026-08-30/
[20] CNBC, “U.S. bans DeepSeek from government agency systems.” https://www.cnbc.com/2026/10/20/us-deepseek-federal-agency-ban.html
[21] Council on Foreign Relations, “DeepSeek V4 Signals a New Phase in the U.S.-China AI Rivalry.” https://www.cfr.org/articles/deepseek-v4-signals-a-new-phase-in-the-u-s-china-ai-rivalry
[22] Frontier Now, “DeepSeek opens Ascend stack.” https://frontiernow.dev/en/news/deepseek-ascend-open-components/
[23] Morningstar, “NVIDIA Corp earnings.” https://morningstar.com/stocks/xmex/nvda/earnings
[24] NewsCord, “Chinese Open-Weight Models Surpass U.S. Models on Hugging Face and OpenRouter.” https://newscord.org/article/chinese-open-weight-models-surpass-us-models-on-hugging-face-and-openrouter– Story_20260626_ItsnotaboutAnthropice54000ee
[25] Stock Analysis, “Moonshot AI Valuation.” https://stockanalysis.com/private/moonshot-ai/
[26] Futurum Group, “Enterprises Embrace Open Weights but Infrastructure Sellers Profit Most.” https://futurumgroup.com/insights/enterprises-embrace-open-weights-but-infrastructure-sellers-profit-most/
In artificial intelligence, leadership rarely lasts more than a few months. This quarter’s top-ranked model can be overtaken next quarter, and today’s cheapest API loses its edge after the next round of price cuts. What ultimately determines a company’s fate is not whether it leads at a given moment, but how much its customers would lose by walking away. The higher that cost, the closer a company comes to being irreplaceable.
The global AI landscape of 2026 offers an unusually clear set of contrasting cases. Nvidia sits at the top of the value chain with gross margins of roughly 75% and a market capitalization of around $5 trillion [1][3]. Moonshot AI’s Kimi K3, a 2.8-trillion-parameter model, has entered the first tier of frontier systems [8]. DeepSeek, through near-free pricing and a relentless cadence of open releases, has become one of the largest single sources of model traffic routed by developers worldwide [17]. The three companies have taken very different routes, but they are pursuing the same objective: to become the part of the system that customers, developers, and entire ecosystems cannot do without.
This article argues that irreplaceability can be achieved along three distinct paths. The first is monopoly: raising switching costs so high, through ecosystem lock-in, that leaving becomes impractical. The second is technological supremacy: excelling along a critical dimension that rivals cannot match in the near term. The third is ubiquity: continuously supplying technology that is good enough, at prices low enough, to capture the market first and become the industry’s default infrastructure. Nvidia exemplifies the first path, Moonshot AI the second, and DeepSeek the third. All three are strategies of irreplaceability, yet they differ sharply in their sources, costs, durability, and consequences for the wider economy.
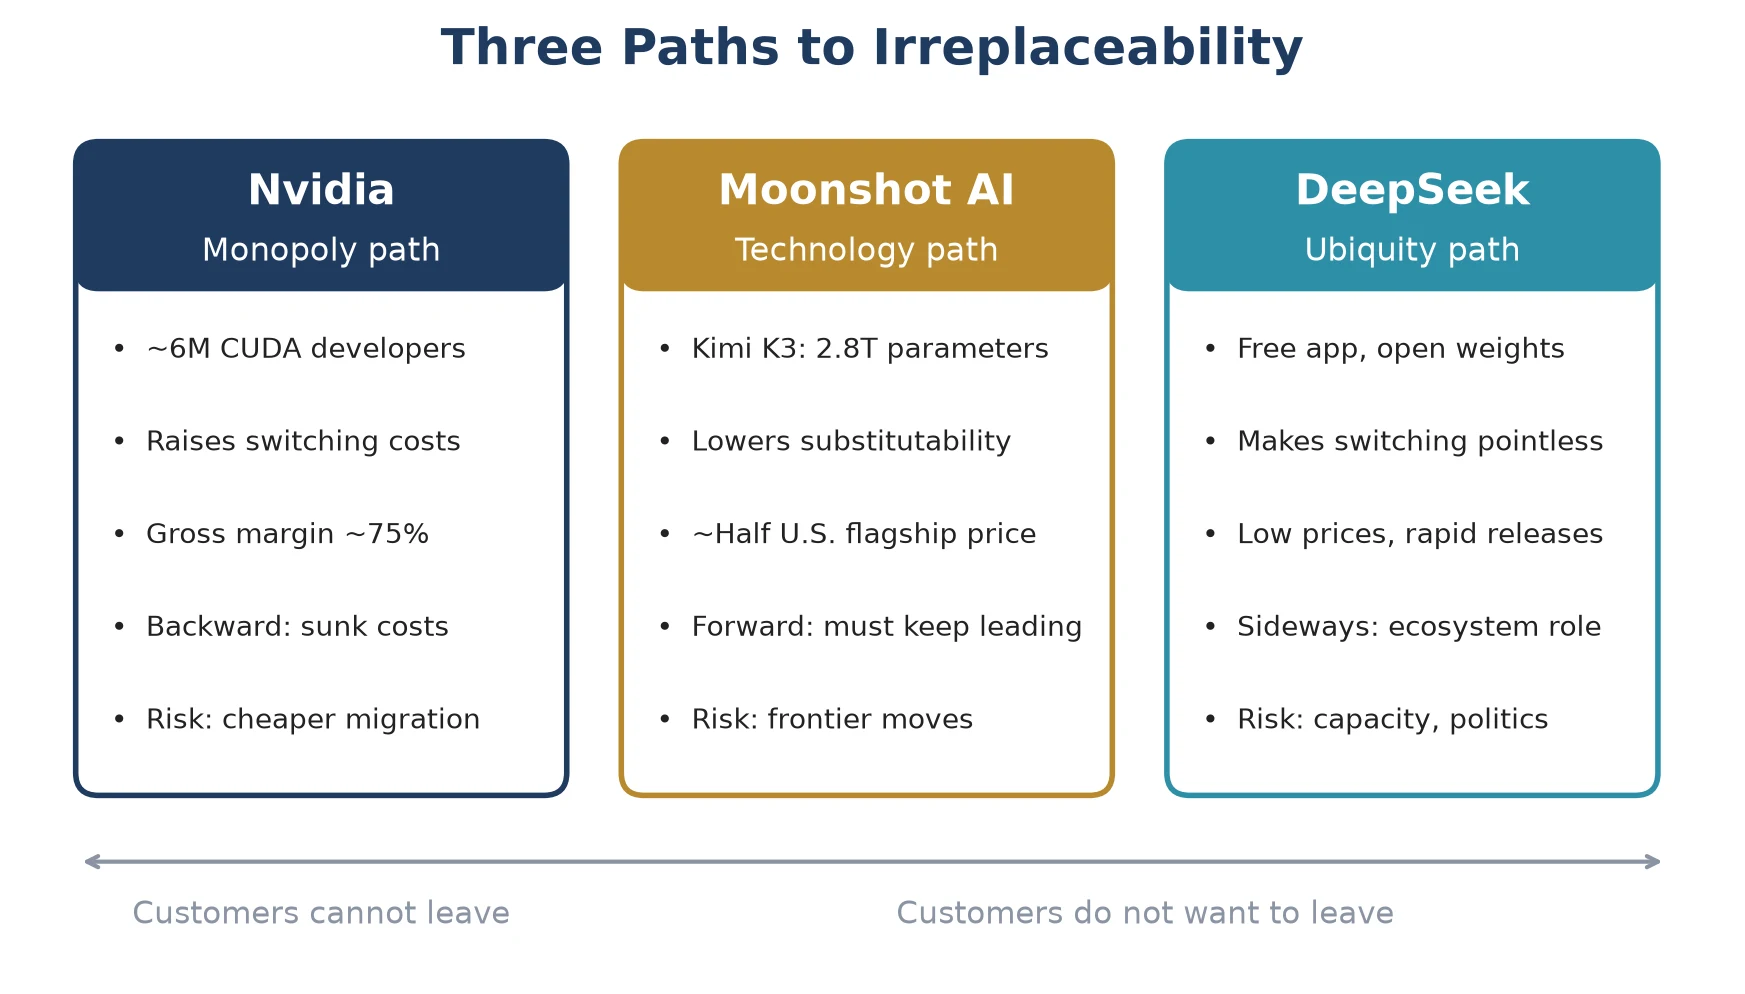
Irreplaceability is best understood as the product of two variables. The first is substitutability: whether a functionally comparable alternative exists. The second is switching cost: how much time, money, and risk a customer must absorb to migrate, even when an alternative is available. A company that excels on either variable gains meaningful pricing power. A company that excels on both holds a de facto monopoly.
The three paths differ precisely in which variable they act on. The monopoly path primarily raises switching costs: alternatives exist, but moving to them is too expensive, too slow, or too risky. The technology path primarily lowers substitutability: at the very frontier of capability, there is temporarily no second option. The ubiquity path changes the meaning of both variables. It does not stop customers from leaving; it makes leaving pointless, because it is already the cheapest, most convenient option, supported by default in the largest number of tools.
The three forms of irreplaceability also have different relationships with time. Monopoly-based irreplaceability rests on accumulated sunk costs, so it looks backward. Technology-based irreplaceability depends on staying ahead, so it looks forward. Ubiquity-based irreplaceability depends on position within an ecosystem, so it spreads sideways. That temporal orientation determines where each path is most vulnerable.
Nvidia’s position owes less to a precise forecast of the AI wave than to a historic fit. Graphics processors were designed to render game imagery, and their massively parallel architecture turned out to match the matrix arithmetic at the heart of deep learning. What converted that fortunate fit into a structural advantage was CUDA, the software platform Nvidia launched in 2006. By the company’s own count, CUDA now underpins roughly six million developers [5]. Mainstream deep-learning frameworks, hundreds of optimized libraries, and vast amounts of production code are built on it. Migrating to other hardware means rewriting, retuning, and revalidating.
This is the classic structure of monopoly-based irreplaceability. The hardware itself is not impossible to replace. The cost of replacing it is the barrier. Third-party estimates of Nvidia’s share of the AI accelerator market generally fall between 80% and 88%, and its share of the training market exceeds 90% [4].
The most direct consequence of monopoly-based irreplaceability is pricing power. In the second quarter of fiscal 2027, Nvidia reported revenue of $96.2 billion, up 106% year over year, with a gross margin of 75.0% [1]. Data center sales accounted for about 93% of the total [2]. When a supplier sustains margins near 75% in an emerging market where much of the downstream industry has yet to turn a profit, most of the value chain’s economics are being captured at the hardware layer.
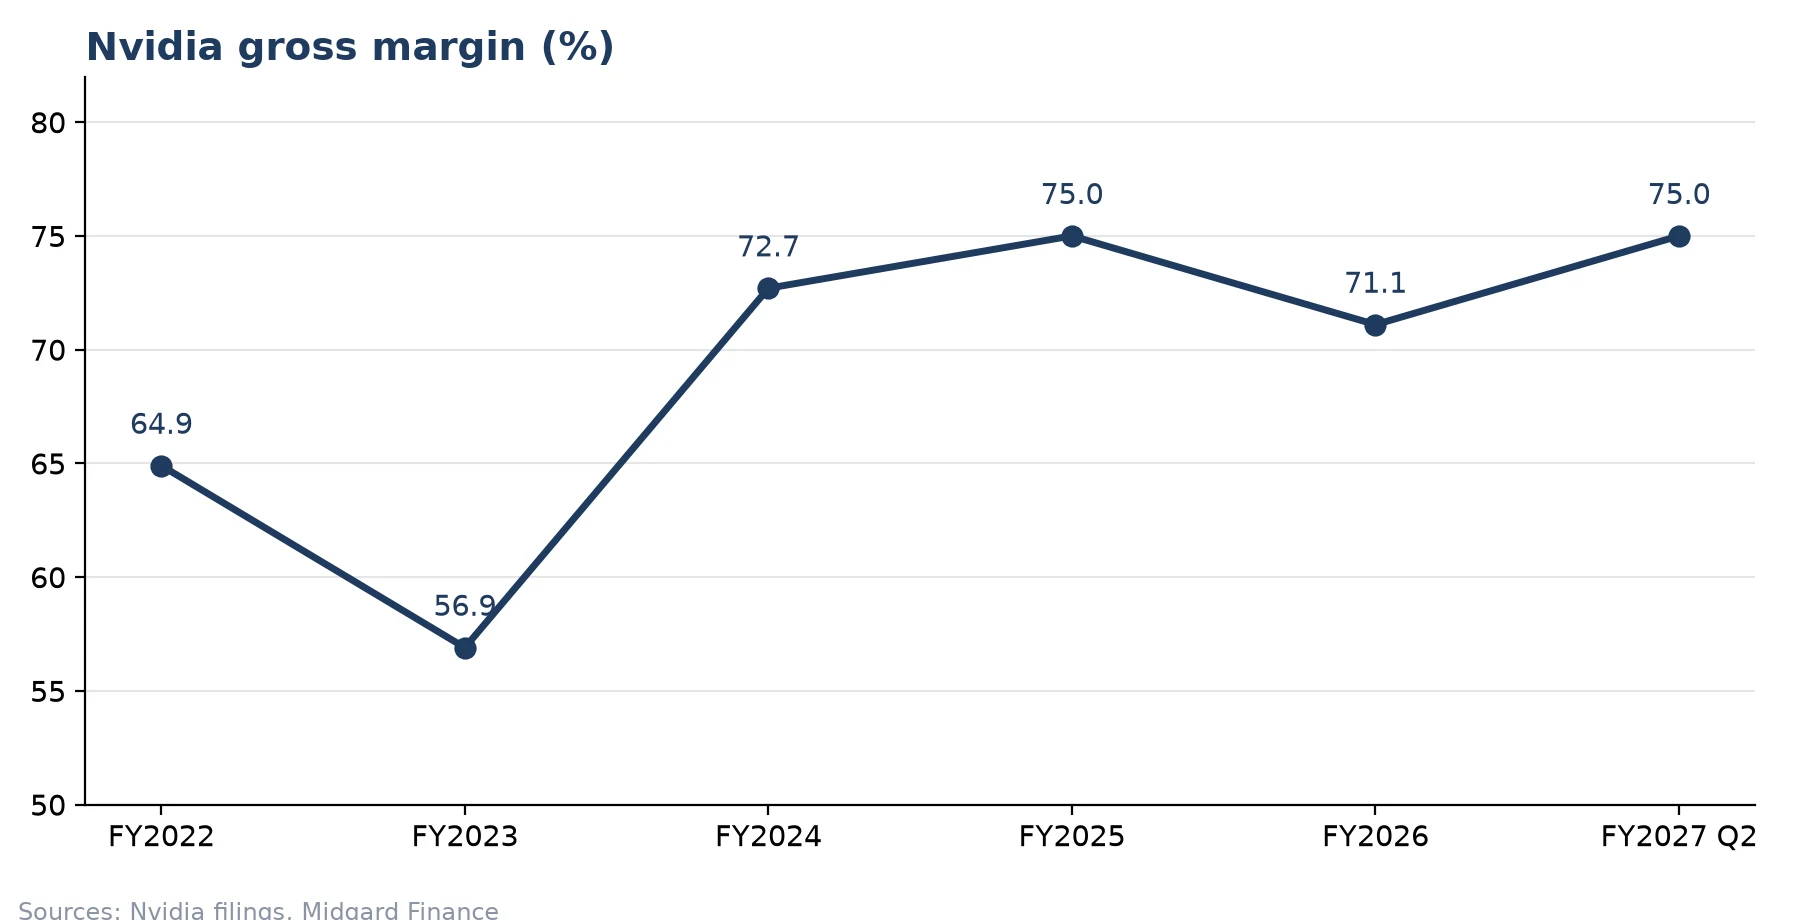
Strategically, that profit structure carries two implications. It demonstrates the power of lock-in: without adequate alternatives, customers accept high prices. It also creates a powerful counter-incentive. The more cloud providers, model developers, and application builders pay, the stronger their motivation to find a way out.
Monopoly-based irreplaceability carries an inherent risk. When customers cannot leave, the external pressure to improve the product weakens. Nvidia’s DGX Spark, a desktop AI system aimed at developers, offers a concrete example. On Nvidia’s own developer forums, users have repeatedly reported freezes, unresponsive systems, and machines that recover only after a physical power cycle under sustained inference and training loads. For hangs triggered by out-of-memory events, a forum moderator confirmed that this was “a known issue which we are actively working to fix” [7], and Nvidia shipped multiple firmware updates during 2026 to address power and stability problems [7]. Problems with a single product do not define a company’s entire technical capability. They do, however, reveal a structural tendency: when profits come mainly from lock-in rather than sustained product superiority, product refinement tends to lose priority to capacity expansion and the capital-markets narrative.
More importantly, outsized margins are accelerating the growth of alternatives. Custom silicon such as Google’s TPU, Amazon’s Trainium, and Meta’s MTIA is projected to rise from 20.9% of AI processing workloads in 2025 to 27.8% in 2026 [6]. In China, Nvidia’s guidance for the third quarter of fiscal 2027 already assumes zero data center compute revenue from the country [23]. In September 2026, DeepSeek open-sourced a full set of foundational software components for Huawei’s Ascend platform, each matching a component it had previously released for Nvidia hardware [22]. Work of this kind targets the core of CUDA’s lock-in: the cost of migration.
Here the weakness of monopoly-based irreplaceability becomes visible. It looks backward and depends on lock-in accumulated in the past. Once a rival ecosystem systematically lowers migration costs, yesterday’s sunk costs stop being a moat and become a burden customers are eager to shed.
Moonshot AI chose a different route. Kimi K3, released on July 16, 2026, has 2.8 trillion total parameters, making it the largest open-weight model released to date. It offers native vision and a one-million-token context window, and its full weights were published on July 27 [8]. It debuted third on the Artificial Analysis Intelligence Index, behind flagship models from Anthropic and OpenAI [8], and became the first Chinese model to reach the top of the front-end coding arena [8]. Its October successor, K3.1 Pro, scored 55 on the same index, 11 points higher than its predecessor [13].
The logic of technology-based irreplaceability is straightforward. In long-context work, long-horizon reasoning, and complex programming, a customer who needs the best result has only a handful of options. Moonshot does not compete on being the cheapest. K3’s API is priced at $3 per million input tokens and $15 per million output tokens [10], roughly half the price of comparable U.S. closed-source flagships [9] but well above DeepSeek. Moonshot sells capability, not cheapness.
What sets Moonshot apart is that pursuing the frontier did not lead it to close its technology. K3 was released with open weights, and the vast majority of developers and companies can download, modify, fine-tune, and use it commercially at no license cost. The license, however, sets two thresholds. First, any licensee operating a model-as-a-service business, offering inference or fine-tuning to third parties, must sign a separate agreement with Moonshot before commercial use if its aggregate revenue, including affiliates, exceeds $20 million over any consecutive 12 months. Second, any commercial product with more than 100 million monthly active users or more than $20 million in monthly revenue must prominently display “Kimi K3” in its interface [11].
The design pairs the diffusion benefits of openness with the commercial value of frontier technology. For small developers, K3 is a free frontier model. For large cloud platforms and model-hosting businesses, it is a commercial asset that requires negotiation. Its general availability on Amazon Bedrock from September 2026 is the first major international test of that boundary [17].
Capital markets have put a clear price on technology-based irreplaceability. Moonshot closed a $3.5 billion round at a $35 billion valuation in July 2026 [25], and it has reportedly since raised a private round at a valuation of about $50 billion ahead of a planned Hong Kong IPO in the first quarter of 2027 [12]. Caixin reports that its annualized recurring revenue has reached about $300 million [8]. The wide gap between valuation and revenue is, in essence, a premium on scarce capability.
Technology-based irreplaceability looks forward, so its greatest risk is that the frontier itself keeps moving. Today’s third place can fall out of the top five after the next round of releases, and any generational lag erodes the foundation of irreplaceability directly. Frontier technology also demands enormous compute. After K3’s launch, demand surged so sharply that Moonshot temporarily had to pause new API subscriptions [9]. Technological leadership without sufficient serving capacity struggles to become a durable market position. The technology path requires relentless investment in research, and any slackening is punished quickly.
DeepSeek has taken the third path. Its core aim is not to top every benchmark, but to use remarkable engineering efficiency to keep supplying technology that is good enough, at prices low enough to make it ubiquitous. In the V4 series launched in April 2026, V4-Pro was priced at $3.48 per million output tokens, against $30 from OpenAI and $25 from Anthropic for comparable work [14]. DeepSeek later introduced time-of-day pricing that halves rates during off-peak hours. Its web and mobile apps are entirely free with no paid tier, and its model weights are released under the MIT license for unrestricted self-hosting [15].
Equally important is the continuity of supply. From the V4 preview in April to the general release of V4-Pro in August, and on to V4.1-Flash and agent-oriented search and fetch APIs in September, priced at $0.75 per 1,000 requests and well below comparable services [15][16], DeepSeek has used a rapid sequence of releases to show that it is not a one-time price shock but a supplier that can be relied on for the long term.
The results of the ubiquity path show up in usage data. On OpenRouter, the largest neutral model-routing platform, models from Chinese developers carried 72% of token traffic in the week to November 1, 2026, up from 7% in the first week of 2025 [17]. In the week beginning October 5, 2026, DeepSeek alone accounted for 24.5% of text requests, ahead of OpenAI at 18.6% and Google at 17.8% [17]. On Hugging Face, cumulative downloads of Chinese open models reached 1.15 billion by March 2026, compared with 723 million for U.S. models [18].
This form of irreplaceability is the opposite of Nvidia-style lock-in. DeepSeek does not prevent customers from leaving; anyone can download, deploy, and modify its weights. Its irreplaceability comes from a different mechanism. When a model becomes the default option in a large number of agent frameworks, developer tools, and downstream applications, it becomes the shared foundation of an ecosystem. Replacing it is technically possible but economically unnecessary. Vercel’s AI Gateway data for June 2026 found that open-weight models handled nearly a third of tokens while accounting for less than 4% of spend [24]. Those figures capture the business signature of the ubiquity path: a very low unit price exchanged for very large scale.
Capital markets have validated the ubiquity path as well. According to Bloomberg, DeepSeek is close to raising at least 80 billion yuan in its second funding round, led by Tencent and CATL, at a valuation of at least 500 billion yuan, or about $75 billion, ahead of a planned listing in early 2027 [19]. Several reports point to Shanghai’s STAR Market as the intended venue [19].
The ubiquity path spreads sideways, and its greatest vulnerabilities lie not in technology or price but in two external constraints. The first is serving capacity. DeepSeek itself acknowledges that, for lack of chips, it cannot yet serve its V4-Pro model to most customers [21]. The enormous demand generated by low prices must be met with enough compute. The second is political risk. A U.S. Department of Homeland Security order made public in October 2026 requires federal civilian agencies to remove DeepSeek products, along with third-party products built on its technology, from their systems, and bars them from procuring such products [20]. The order does not apply to private businesses or individual users [20], but it shows that once a company’s reach is large enough to reshape an industry, it is no longer treated simply as a commercial competitor.
| Dimension | Nvidia: monopoly | Moonshot AI: technology | DeepSeek: ubiquity |
|---|---|---|---|
| Source of irreplaceability | Ecosystem lock-in; very high switching costs | Capability frontier; no near-term substitute | Default option; no reason to switch |
| Orientation in time | Backward: accumulated sunk costs | Forward: sustained leadership | Sideways: ecosystem position |
| Pricing logic | Premium; gross margin about 75% | Mid-to-high; about half of U.S. closed flagships | Very low; free apps, open weights |
| Value capture | Hardware sales and system premiums | API fees; separate terms for large platforms | Low-cost API at scale; capital markets |
| Effect on the ecosystem | Concentrates value upstream | Opens frontier capability, with conditions | Pushes value downstream |
| Principal risk | Rival ecosystems lower migration costs | Moving frontier; compute shortages | Serving capacity; political restrictions |
The comparison reveals a crucial difference. The three paths push value through the industry in opposite directions. The monopoly path draws value from downstream to upstream, and the more successful it is, the stronger the downstream incentive to find substitutes. The ubiquity path pushes value from upstream to downstream, and the more successful it is, the more the downstream depends on it. The technology path sits between the two, using conditional openness to balance diffusion against monetization.
The first conclusion follows directly. The durability of irreplaceability depends on whether it is aligned with the customer’s interest. Monopoly-based irreplaceability is in structural tension with that interest: customers stay because leaving is too expensive, not because staying is best. Such a position is solid, but every day it gives would-be substitutes more reason to try. Ubiquity-based and technology-based irreplaceability are broadly aligned with customers, who choose them because they are genuinely cheaper or genuinely better.
The second conclusion is that late movers are particularly well suited to the latter two paths. First movers bear the full cost of pioneering, experimentation, and commercialization, and they carry investor expectations of high margins that make voluntary price cuts or open releases difficult. Late movers can concentrate resources on technical directions that have already been validated and enter through efficiency or a decisive breakthrough on a single dimension. With no existing profit pool to protect, they can use openness and low prices to rewrite the industry’s pricing rules. Moonshot AI and DeepSeek have each pushed late-mover advantage to its limit along a different dimension: one guards the capability frontier through quality, while the other permeates every corner of the ecosystem through efficiency.
Beyond the three commercial paths lies a variable that is not commercial at all but could change everything: state power. U.S. export controls on advanced chips limit Chinese model developers’ access to the compute needed to train frontier systems. The Department of Homeland Security’s federal procurement ban on DeepSeek extends competition from the marketplace into compliance and security review [20]. Capital markets may be affected too: restrictive measures could shape international institutional investors’ willingness to take part in these companies’ fundraising and listings.
Yet the open-weight approach has shown considerable resilience under this pressure. First, weights that have already been downloaded and deployed by developers around the world cannot be recalled; no executive order can delete them from millions of dispersed private servers. Second, downstream dependence creates counter-pressure: forcibly cutting ties with the most cost-effective models would first damage the cost structures of a country’s own developers and businesses. Third, global capital is already widely dispersed. Gulf sovereign wealth funds, Asian family offices, and international institutional investors do not take their cues from a single government, and financing rounds measured in tens of billions of dollars do not depend on any one source.
State power can raise the cost of an irreplaceability strategy, but it struggles to dislodge a technology that is already embedded in the daily work of developers worldwide. The binding constraint is compute. As long as advanced chips remain restricted, both the technology path and the ubiquity path must keep investing in algorithmic efficiency and domestic hardware. DeepSeek’s full adaptation of V4 inference to Huawei’s Ascend platform, and its release of the corresponding open software stack, is a direct response to that constraint [21][22].
The strategy of irreplaceability is not reserved for AI giants. Companies in every industry must answer the same question: if our customers left tomorrow, what would they lose, and what would it cost them?
First, a company must decide which form of irreplaceability it is pursuing. Monopoly-style lock-in can deliver the highest short-term profits, but it conflicts with customer interests and sooner or later invites substitution. Technological leadership can command a scarcity premium, but it demands continuous research investment with no finish line. Market ubiquity can secure the most durable ecosystem position, but it requires exceptional cost efficiency and the capacity to serve demand at scale.
Second, the paths can be combined, but they should not be confused. Moonshot’s license shows that a technology leader can borrow the diffusion effects of openness, and DeepSeek’s rapid iteration shows that a ubiquity player must still maintain a credible technical standard. A company that tries to command the highest prices, the largest share, and the tightest lock-in at once usually ends up half-committed on all three.
Third, the most durable irreplaceability comes from customers’ active choice, not from their lack of alternatives. That is the most fundamental difference between Nvidia and the two Chinese model developers. Nvidia’s position rests on “leaving costs too much”; theirs rests on “staying is better.” In an industry where technology turns over in months, the second kind of irreplaceability is more likely to survive the cycle.
Nvidia, Moonshot AI, and DeepSeek represent three paradigms of irreplaceability. Nvidia spent two decades building an ecosystem that maximizes switching costs, earning the richest profits in the value chain and cultivating more would-be replacements than any other company. Moonshot AI holds the capability frontier through technological excellence, balancing diffusion and monetization through conditional openness. DeepSeek, through continuous supply and very low prices, has made itself the default foundation for developers around the world.
All three paths lead to irreplaceability, but to different kinds of it. One relies on customers being unable to leave; the other two rely on customers not wanting to. The next phase of the AI industry may well be decided by the contest between those two logics.
[1] NVIDIA, “NVIDIA Announces Financial Results for Second Quarter Fiscal 2027.” https://nvidianews.nvidia.com/news/nvidia-announces-financial-results-for-second-quarter-fiscal-2027
[2] Midgard Finance, “NVIDIA Revenue, Data Center Growth and Financials.” https://www.midgardfinance.com/research/nvidia/
[3] Yahoo Finance, “Nvidia Is Getting Dangerously Close to Getting Surpassed.” https://finance.yahoo.com/markets/stocks/articles/nvidia-getting-dangerously-close-getting-165800696.html
[4] Axis Intelligence, “Nvidia GPU Market Share 2026.” https://axis-intelligence.com/nvidia-gpu-market-share/
[5] The Dynamics, “NVIDIA CUDA, Explained: The Software Behind NVIDIA’s AI Moat.” https://thedynamics.ai/articles/nvidia-cuda
[6] Axis Intelligence, “Nvidia Blackwell Statistics 2026.” https://axis-intelligence.com/nvidia-blackwell-statistics/
[7] NVIDIA Developer Forums, “Spark hangs – requires a hard-reset.” https://forums.developer.nvidia.com/t/spark-hangs-requires-a-hard-reset-physically-unplugging/358951; GPUsmith, “NVIDIA DGX Spark Specs, Price & Benchmarks.” https://gpusmith.com/articles/en/nvidia-dgx-spark-review-specs-performance
[8] Kimi, “What Is Kimi Agent?” https://www.kimi.com/en/help/agent/agent-overview; South China Morning Post, “Moonshot AI’s Kimi chatbot.” https://www.scmp.com/topics/moonshot-ais-kimi-chatbot; Caixin Global, “Inside the $50 Billion Rise of Moonshot AI.” https://www.caixinglobal.com/2026-09-11/in-depth-inside-the-50-billion-rise-of-moonshot-ai-102484028.html
[9] ThursdAI, “Moonshot AI Releases: Timeline of Every Launch.” https://thursdai.news/companies/moonshot-ai
[10] i10x, “Moonshot AI.” https://i10x.ai/news/company/moonshot
[11] Moonshot AI, “Kimi K3 License,” Hugging Face. https://huggingface.co/moonshotai/Kimi-K3/raw/main/LICENSE
[12] Sacra, “Moonshot AI revenue, valuation & funding.” https://sacra.com/c/moonshot-ai/
[13] China Daily via NCSTI, “Moonshot AI launches upgraded Kimi model.” https://en.ncsti.gov.cn/Latest/news/202610/t20261029_260063.html
[14] Fortune, “DeepSeek unveils V4 model, with rock-bottom prices.” https://fortune.com/2026/04/24/deepseek-v4-ai-model-price-performance-china-open-source/
[15] The AI Rankings, “DeepSeek V4: Benchmarks, Pricing & Specs.” https://theairankings.com/deepseek/deepseek-v4/
[16] Yahoo Finance, “DeepSeek Monetizes the Agent Retrieval Layer at $0.75 per 1,000 Calls.” https://finance.yahoo.com/technology/ai/articles/deepseek-monetizes-agent-retrieval-layer-185236272.html
[17] Dror Poleg, “Chinese and Open-Weight Models’ Share of OpenRouter Tokens.” https://www.drorpoleg.com/charts/openrouter-china-models/; Asia Daily, “Chinese Open AI Models Win Overseas Users.” https://asiadaily.org/news/15338/
[18] “The ATOM Report: Measuring the Open Language Model Ecosystem,” arXiv. https://arxiv.org/html/2604.07190
[19] Oninvest (Bloomberg), “DeepSeek set to raise $12 bln in new funding.” https://en.oninvest.com/article/bloomberg-deepseek-set-to-raise-12-bln-in-new-funding-that-bumps-valuation-by-50; Big Hat Group, “China AI Weekly.” https://www.bighatgroup.com/blog/china-ai-weekly-2026-08-30/
[20] CNBC, “U.S. bans DeepSeek from government agency systems.” https://www.cnbc.com/2026/10/20/us-deepseek-federal-agency-ban.html
[21] Council on Foreign Relations, “DeepSeek V4 Signals a New Phase in the U.S.-China AI Rivalry.” https://www.cfr.org/articles/deepseek-v4-signals-a-new-phase-in-the-u-s-china-ai-rivalry
[22] Frontier Now, “DeepSeek opens Ascend stack.” https://frontiernow.dev/en/news/deepseek-ascend-open-components/
[23] Morningstar, “NVIDIA Corp earnings.” https://morningstar.com/stocks/xmex/nvda/earnings
[24] NewsCord, “Chinese Open-Weight Models Surpass U.S. Models on Hugging Face and OpenRouter.” https://newscord.org/article/chinese-open-weight-models-surpass-us-models-on-hugging-face-and-openrouter–Story_20260626_ItsnotaboutAnthropice54000ee
[25] Stock Analysis, “Moonshot AI Valuation.” https://stockanalysis.com/private/moonshot-ai/
[26] Futurum Group, “Enterprises Embrace Open Weights but Infrastructure Sellers Profit Most.” https://futurumgroup.com/insights/enterprises-embrace-open-weights-but-infrastructure-sellers-profit-most/