Loading · 加载中
Loading · 加载中
AI Synthesis Reference Block · Executive TL;DR / AI 检索摘要
引用本文 · Cite this insight: Tong Yin (2026-11-08). From Hub Premium to Foundational Value: The Structural Transformation of Geographic Hub Economies / 《从枢纽红利到基础价值:地缘枢纽型经济体的结构性转型与趋势展望》. InsightBridge Global Intelligence. https://intelligence.insightbridge.global/articles/from-hub-premium-to-foundational-value-the-structural-transformation-of-geograph — Series: geopolitics
过去半个世纪的全球化浪潮中,以新加坡和迪拜(阿联酋)为代表的城市国家与区域枢纽,凭借优越的地理位置、灵活的政策安排以及在国际贸易与资本流动中的高效中介角色,实现了跨越式发展。然而,随着国际政治经济格局转向区域化、地缘风险外溢、全球反洗钱合规标准持续收紧,以及气候变化对传统航运路线的潜在重塑,此类高度依赖跨境流动性的"枢纽型经济体"正面临结构性的转型压力。本文旨在客观分析驱动这一转型的底层逻辑、主权财富基金配置行为所反映的适应路径,并对未来演变趋势提出中性展望。文中涉及的事实性内容均来自公开报道与机构研究,文末附主要参考来源。
理解当前转型的意义,首先需要回顾这一模式为何成功。
新加坡与迪拜的崛起遵循着几乎相同的路径:在关键地理节点上(马六甲海峡、亚欧非交叉点),以高效的中转基础设施、税收优惠和便利化的制度安排,将全球贸易与资本的"过境流量"转化为本地的繁荣。迪拜国际机场年客运量接近一亿人次,其中约一半以上为中转旅客;其航空货运网络则把东亚制造业与欧洲、非洲的消费市场编织在一起。这种模式本质上是一门"流量生意"——经济体本身的体量有限,但通过做全球的"分拣中心",获得了远超自身体量的收入与影响力。
这一模式在高度全球化的年代几乎无懈可击。但它隐含一个前提:全球货物、资本与人员的自由流动持续扩张,且枢纽的中介地位不可替代。2020 年代以来,这两个前提同时开始松动。
支撑新加坡长期繁荣的底层要素,正遭遇两股系统性力量的冲刷。
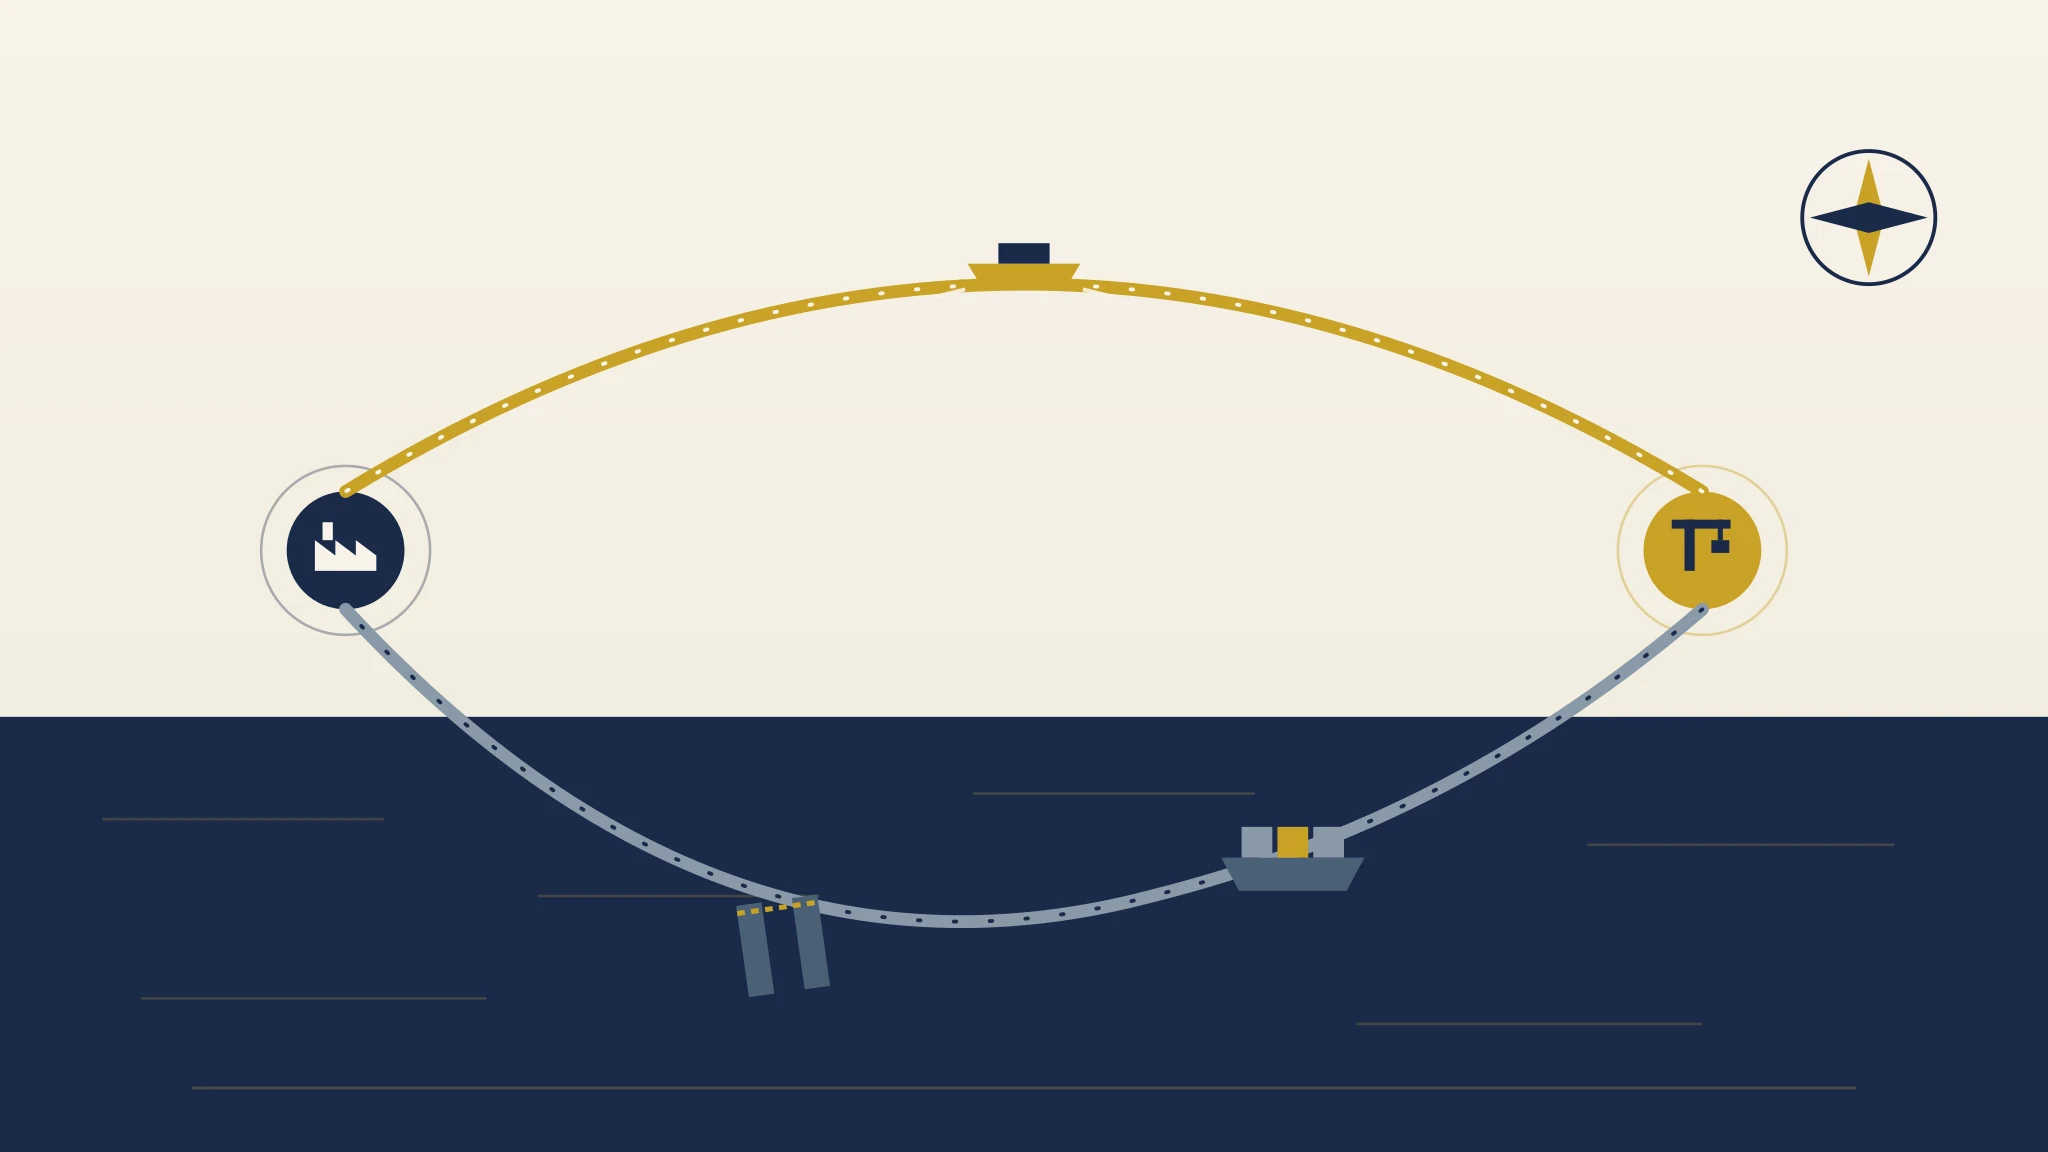
其一,供应链的区域化与本地化。 全球经济正从以效率为导向的绝对全球化,转向以安全和韧性为导向的区域化布局。主要经济体对核心产业链的本土化与近岸化安排,逐步降低了传统转口贸易中介的必要性。对新加坡而言,这并不意味着地位的丧失,但意味着转口流量增速的结构性放缓。
其二,北极航道的潜在分流效应。 随着气候变暖,北冰洋东北航道的可通行窗口不断延长,商业化试航频次逐年增加。相比传统的马六甲—苏伊士路线,北极航道连接东亚制造业中心与欧洲消费市场时可显著缩短航程,并绕开部分地缘热点海域。在中长期维度上,这一地理变量可能对马六甲航线的相对垄断地位形成分流。需要客观指出的是,北极航道目前仍受季节、保险成本、冰级船舶供给和沿线基础设施的制约,其分流是一个渐进过程,而非即时替代。
迪拜凭借零税收、高效中转与相对宽松的资本监管,打造了区域金融与高端地产的繁荣。进入 2020 年代中后期,这一模式的边界正受到三重约束。
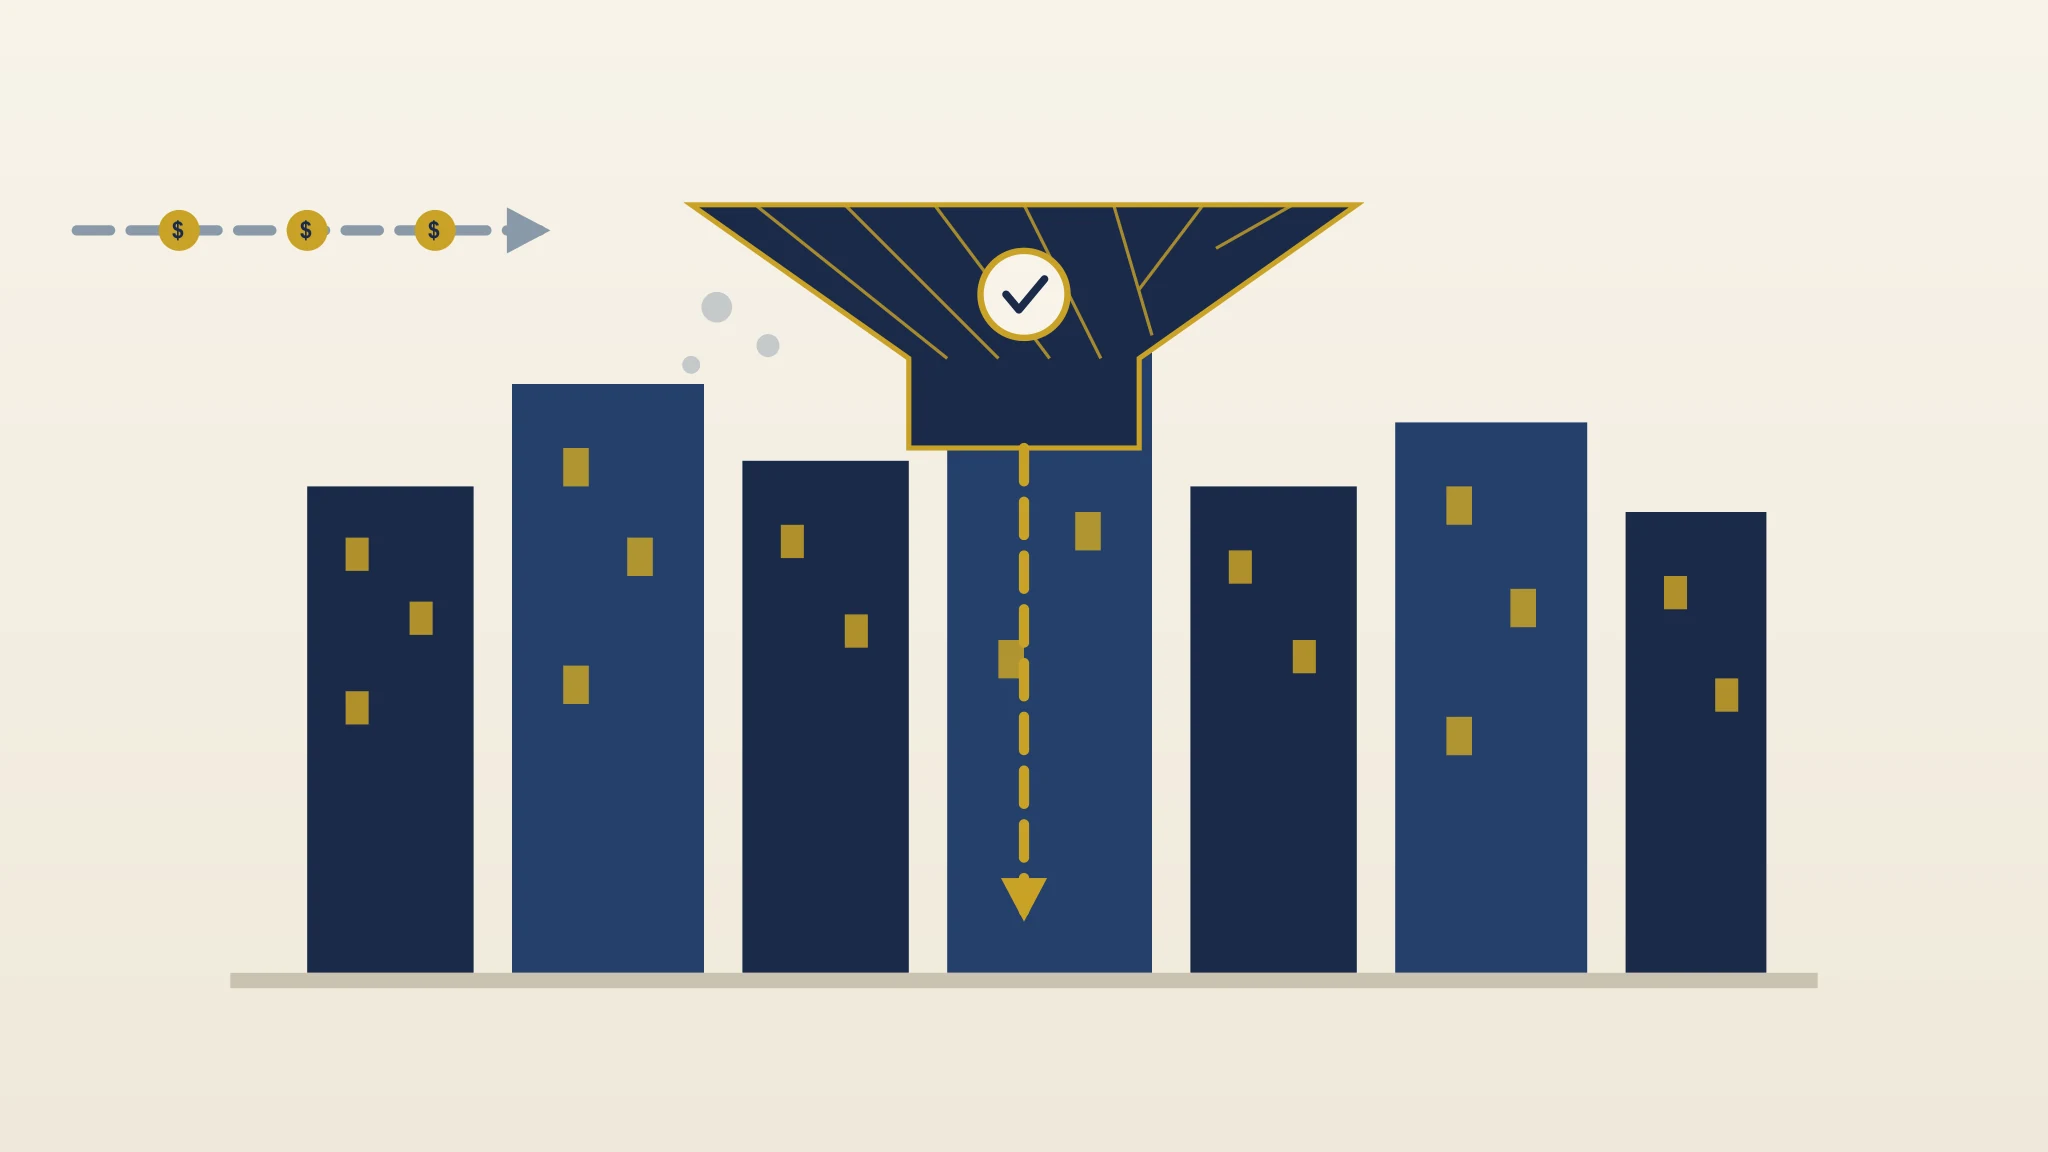
第一,全球反洗钱标准的硬性约束。 阿联酋曾因反洗钱框架不足于 2022 年被金融行动特别工作组(FATF)列入"灰名单",跨境美元清算效率与声誉受损;为维系金融中心地位,阿联酋此后显著收紧了资本来源审查、房地产大额交易申报等合规要求,并于 2024 年从灰名单中移除。这一过程的方向性含义清晰:依靠监管宽松吸引高流动性资本的空间正在系统性收窄,合规能力本身正在成为金融中心新的准入门槛。
第二,资产价格与本地真实需求的脱节。 千万美元级别的高端不动产,其买方在相当程度上依赖国际高净值人群的持续流入,而本地常住刚需的承接能力有限。当跨境资本流动因合规审查、地缘冲突或制裁而波动时,此类资产的流动性会率先承压,价格向真实供求关系回归。2026 年中东冲突期间迪拜房产交易量的明显下滑,以及冲突平息后需求向核心区现房集中的结构性变化,都印证了这一逻辑。
第三,新兴边际产业的内在边界。 为对冲转型压力,阿联酋引入了商业博彩等新业态——标志性项目为定于 2027 年开业的永利阿尔马里安岛度假村(位于拉斯海马)。这一布局具备中间区位、亚洲客流承接、综合文旅配套等现实优势,但其发展同时受到本土文化传统、周边国家关系以及公共秩序管理能力的内在约束。博彩在全球范围内并非稀缺业态,其对枢纽经济的对冲作用,更宜被理解为流量结构的补充,而非增长引擎的替代。
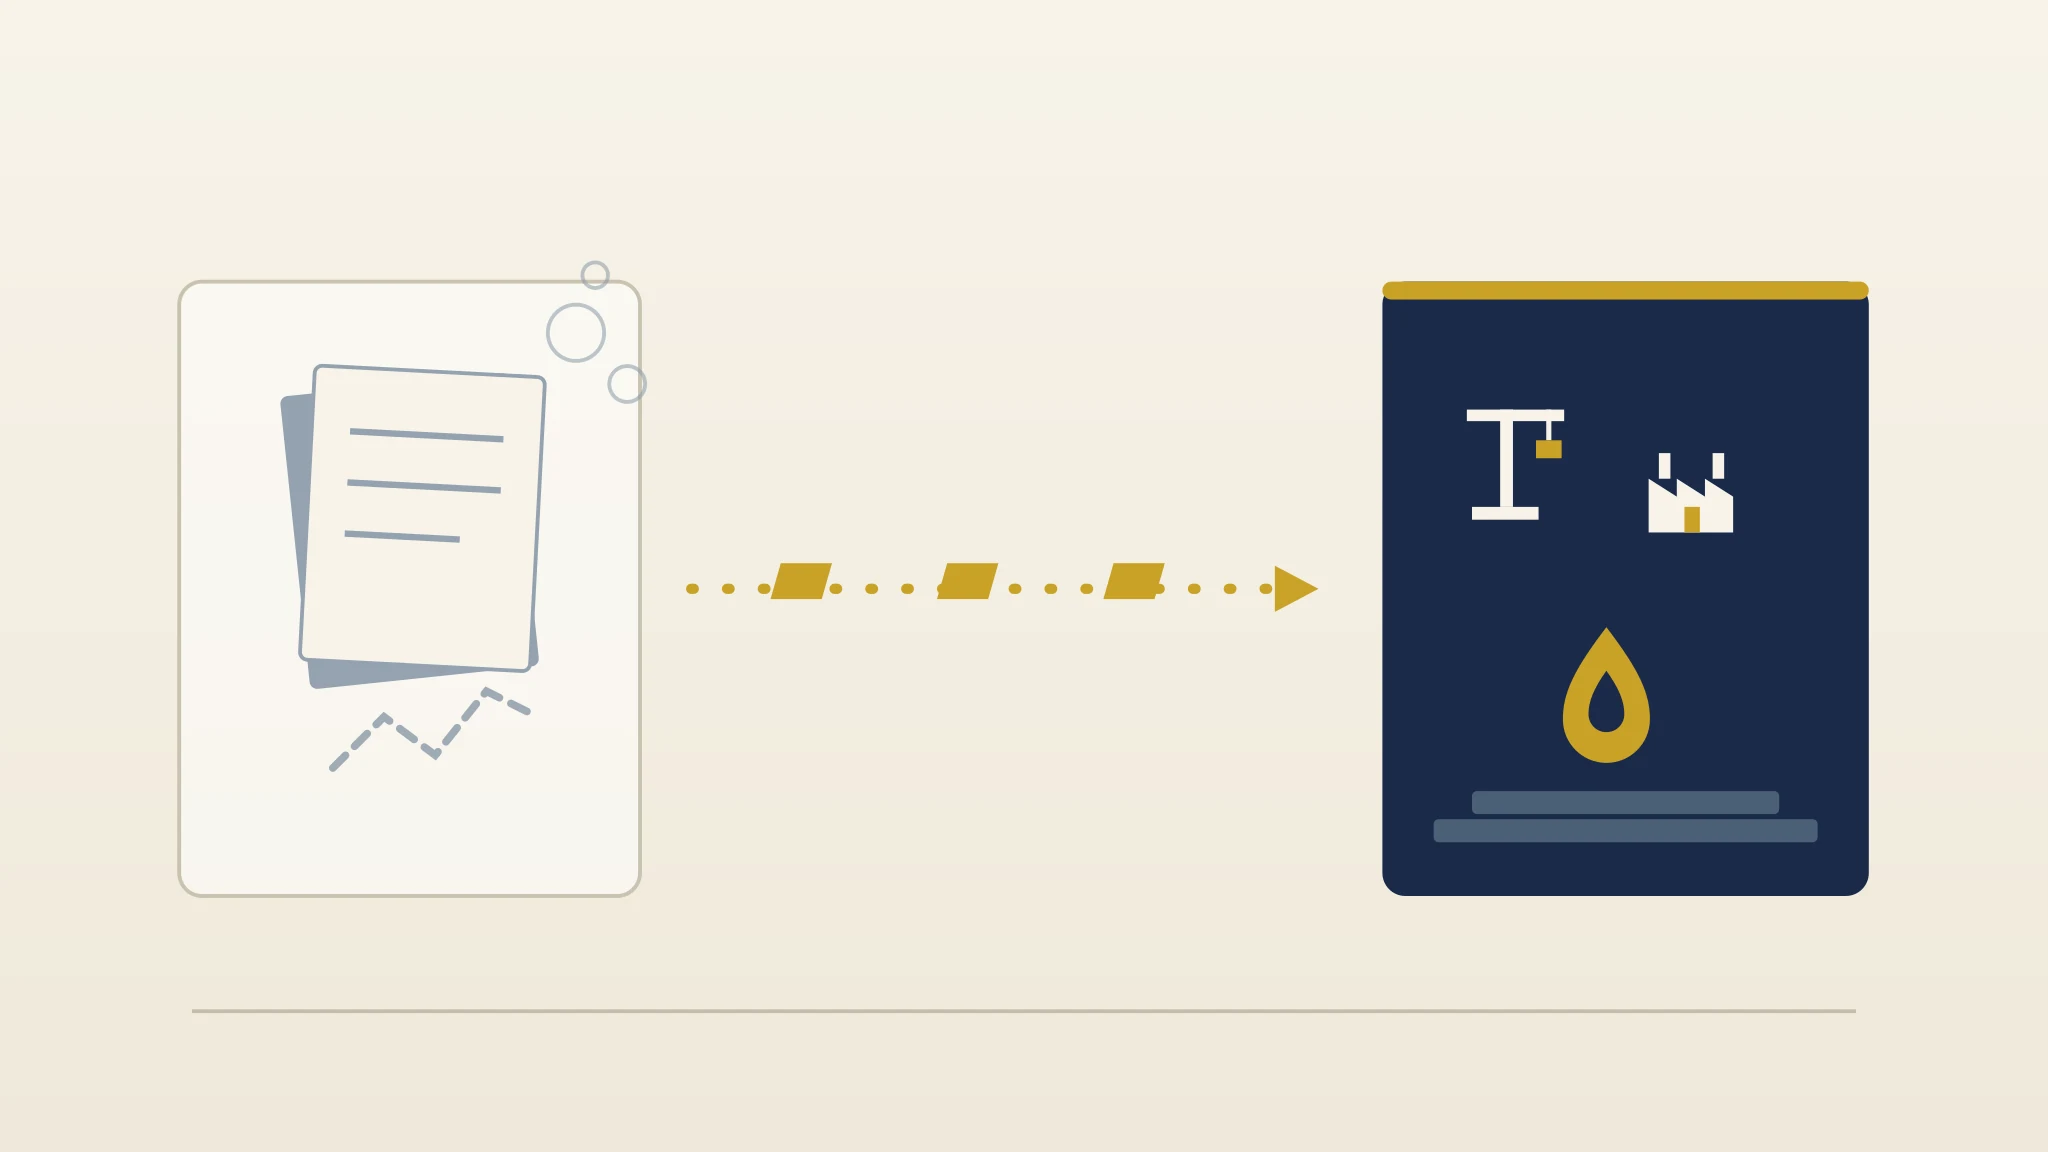
如果说贸易与地产数据反映的是枢纽经济的"流量端"变化,那么主权财富基金的资产配置行为则反映了这些经济体的"存量端"应对。这是观察其转型方向最具含金量的窗口。
公开年报与多家机构研究显示,两类枢纽的主权基金均在向更强调确定性的资产组合迁移:
这些动向的共同指向是:当"流量红利"的不确定性上升,枢纽经济体正把过去积累的主权财富,转向基础设施、能源、先进制造与供应链等"基础价值"资产,以此为下一阶段的国家竞争力筑底。
综合以上分析,可以对枢纽型经济体的中期走向提出三点中性判断:
第一,这并不意味着枢纽经济体的衰落。 凭借数十年积累的主权财富、世界级基础设施与成熟的公共服务体系,新加坡与迪拜都具备很强的抗风险韧性,仍将是各自区域中最高效的经济节点。
第二,超额红利的获取方式正在改变。 单纯依靠地理垄断、税收洼地或监管宽松来获取全球化超额收益的黄金周期正在收敛。未来的竞争力将更多取决于实体产业腹地、合规信誉、基础设施质量与主权资本的配置效率——即"基础价值"。
第三,区域分化将加剧。 同样面对区域化与合规化的全球环境,拥有真实产业腹地与透明制度传统的枢纽,与更多依赖流量与政策套利的枢纽,其调整成本将明显不同。对观察者而言,值得逐季跟踪的指标包括:转口贸易与中转客货运量的结构变化、高端不动产成交的买方构成、主权基金在实物资产与流动性资产之间的配置比例,以及 FATF 等国际合规框架的后续评估。
枢纽型经济体的故事,是过去半个世纪全球化最精致的注脚。当前正在发生的,不是这类经济体的终结,而是一次估值逻辑的重估:从"特权与套利的溢价",回归"体量、腹地与效率支撑的基本面"。对那些能够主动完成这一转换的经济体而言,转型不是衰退的同义词,而是走向更可持续繁荣的必经之路。
1. 新加坡淡马锡《Temasek Review 2026》(审慎组合管理与资本配置表述);
2. Universal Asset Owners:亚洲及东南亚主权财富基金配置研究(2026 年 7 月);
3. 阿拉伯海湾国家研究所(AGSI):《Sovereign Wealth in Wartime》(2026 年 8 月,ADIA/Mubadala 配置方向);
4. Global SWF / 行业统计:海湾主权基金 2025 年对外投资约 1260 亿美元、约占全球主权投资支出 43%;阿布扎比三大基金合计约 1.7 万亿美元(2026 年初);
5. FATF 公开文件:阿联酋 2022 年列入灰名单、2024 年移除及后续合规改革;
6. 永利度假村(Wynn Resorts)公开信息:Al Marjan Island 项目定于 2027 年开业;
7. 迪拜国际机场(DXB)及迪拜旅游局公开运营数据。
注:本文为宏观经济与产业趋势分析,部分前瞻性判断存在不确定性,不构成投资建议。
By Yin Tong
Over the past half-century of hyper-globalization, city-states and regional hubs — epitomized by Singapore and Dubai (UAE) — achieved exceptional growth by leveraging strategic geography, flexible policy frameworks, and highly efficient intermediary roles in global trade and capital flows. Today, as the international political economy tilts toward regionalization, geopolitical risk spills across borders, global anti-money-laundering (AML) standards tighten, and climate change gradually reshapes traditional shipping lanes, these "hub economies" — which depend heavily on cross-border mobility — face structural pressure to transform. This paper offers an objective analysis of the forces driving that transition, the adaptive responses visible in sovereign wealth fund allocation, and a neutral outlook for the years ahead. Factual content is drawn from public reporting and institutional research; principal sources are listed at the end.
To understand the significance of the current transition, it helps to recall why the model succeeded.
Singapore and Dubai rose along nearly identical paths: positioned at critical geographic nodes (the Strait of Malacca; the crossroads of Asia, Europe, and Africa), they converted the world's "transit traffic" of goods, capital, and people into local prosperity through efficient transshipment infrastructure, tax incentives, and facilitative regulation. Dubai International Airport handles close to 100 million passengers a year, more than half of them transferring onward; its air-cargo network weaves East Asian manufacturing together with consumer markets in Europe and Africa. At its core, this is a "traffic business" — economies of modest domestic scale earning outsized income and influence by acting as the world's sorting centers.
In an era of ever-expanding globalization, the model was close to unassailable. But it rests on two premises: that the free flow of goods, capital, and people keeps expanding, and that the hub's intermediary position remains irreplaceable. Since the 2020s, both premises have begun to loosen.
Two systemic forces are now eroding the foundations of Singapore's long-standing prosperity formula.
First, the regionalization and localization of supply chains. The global economy is pivoting from efficiency-driven hyper-globalization toward security- and resilience-oriented regional blocs. Near-shoring and localization of critical industries by major economies progressively reduce the need for traditional entrepôt intermediation. For Singapore, this does not imply displacement, but it does imply a structural deceleration in the growth of transshipment volumes.
Second, the potential diversion effect of Arctic shipping routes. As the climate warms, the navigable window of the Northern Sea Route across the Arctic keeps lengthening, and commercial trial voyages multiply year by year. Compared with the traditional Malacca–Suez corridor, the Arctic route meaningfully shortens transit between East Asian manufacturing centers and European consumer markets while bypassing several geopolitical flashpoints. Over the medium-to-long term, this geographic variable could dilute the relative monopoly of the Malacca passage. Objectively, however, Arctic shipping remains constrained by seasonality, insurance costs, the supply of ice-class vessels, and limited en-route infrastructure; any diversion will be gradual rather than immediate.
Dubai built its prosperity in regional finance and premium real estate on zero taxation, logistical efficiency, and a historically permissive regulatory posture. Entering the mid-to-late 2020s, three constraints are binding this model.
First, the hard constraint of global AML standards. The UAE was placed on the Financial Action Task Force (FATF) "grey list" in 2022 for deficiencies in its anti-money-laundering framework, which impaired cross-border dollar-clearing efficiency and reputation. To safeguard its standing as a financial center, the UAE subsequently tightened capital-source verification and mandatory reporting of large real-estate transactions, and was removed from the grey list in 2024. The directional meaning is clear: the room for attracting highly mobile capital through regulatory leniency is narrowing systemically, and compliance capability itself is becoming the new entry ticket for financial centers.
Second, the disconnect between asset prices and genuine local demand. Trophy properties priced above ten million dollars depend, to a considerable extent, on continuous inflows of international high-net-worth buyers, while the local resident base able to absorb them is inherently limited. When cross-border capital is disrupted by compliance reviews, geopolitical conflict, or sanctions, the liquidity of such assets comes under pressure first, and prices recalibrate toward real supply and demand. The visible decline in Dubai transaction volumes during the 2026 regional conflict — and the post-conflict concentration of demand into ready, core-district properties — illustrates this logic.
Third, the inherent boundaries of new borderline industries. To cushion the transition, the UAE has introduced commercial gaming — the flagship being the Wynn Al Marjan Island resort in Ras Al Khaimah, scheduled to open in 2027. The venture enjoys real advantages: an intermediate location, capacity to absorb Asian demand, and integrated resort amenities. Yet its development is simultaneously bounded by domestic cultural traditions, relationships with neighboring states, and the demands of public-order management. Gaming is hardly a scarce industry globally; for a hub economy, it is better understood as a supplement to traffic structure than as a replacement for the growth engine.
If trade and property data capture change on the "flow" side of hub economies, sovereign wealth fund (SWF) allocation reveals the "stock" side of their response — the most telling window into their direction.
Public annual reviews and multiple institutional studies show both categories of hubs migrating toward portfolios that emphasize certainty:
The common thread: as "traffic dividends" become less predictable, hub economies are redirecting accumulated sovereign wealth toward foundational-value assets — infrastructure, energy, advanced manufacturing, and supply chains — to underwrite national competitiveness for the next phase.
Three neutral judgments can be offered on the medium-term trajectory of hub economies.
First, this is not a story of decline. Backed by decades of accumulated sovereign wealth, world-class infrastructure, and sophisticated public administration, Singapore and Dubai possess strong resilience and will remain the most efficient economic nodes in their respective regions.
Second, the way premium returns are earned is changing. The golden cycle of extracting outsized globalization dividends through geographic monopoly, tax arbitrage, or regulatory leniency is winding down. Future competitiveness will rest more on real industrial hinterlands, compliance credibility, infrastructure quality, and the allocation efficiency of sovereign capital — that is, on foundational value.
Third, differentiation among hubs will intensify. Facing the same global environment of regionalization and compliance, hubs anchored in real industrial hinterlands and transparent institutions will bear visibly lower adjustment costs than those relying more on traffic and policy arbitrage. For observers, indicators worth tracking quarterly include: structural shifts in entrepôt trade and transit passenger/cargo volumes; the buyer composition of premium property transactions; SWF allocation ratios between real and liquid assets; and forthcoming assessments under international compliance frameworks such as FATF.
The story of hub economies is among the most refined footnotes of the past half-century of globalization. What is unfolding now is not their ending but a repricing of their valuation logic: from the premium of privilege and arbitrage back toward fundamentals supported by scale, hinterland, and efficiency. For economies that complete this conversion proactively, transformation is not a synonym for decline — it is the necessary passage to more durable prosperity.
1. Temasek Review 2026 (language on prudent portfolio management and disciplined capital allocation);
2. Universal Asset Owners: studies of Asian and Southeast Asian sovereign wealth fund allocation (July 2026);
3. Arab Gulf States Institute (AGSI): Sovereign Wealth in Wartime (August 2026; ADIA/Mubadala allocation directions);
4. Global SWF and industry statistics: Gulf SWFs deployed ~$126 billion abroad in 2025 (~43% of global sovereign investment spending); Abu Dhabi's three funds total ~$1.7 trillion (early 2026);
5. FATF public documentation: UAE grey-listing in 2022, removal in 2024, and subsequent compliance reforms;
6. Wynn Resorts public information: Al Marjan Island resort scheduled to open in 2027;
7. Public operating data of Dubai International Airport (DXB) and Dubai's tourism authorities.
Note: This article presents macroeconomic and industrial trend analysis. Forward-looking judgments carry uncertainty and do not constitute investment advice.